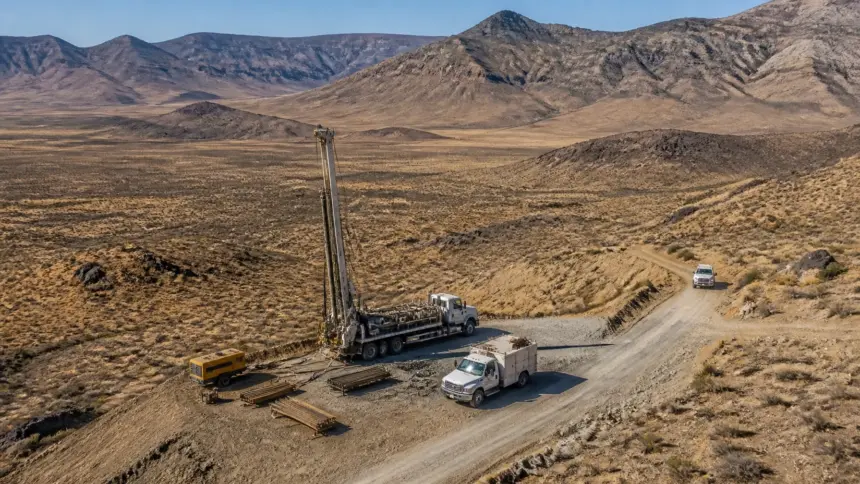
An exploration drill rig works across Nevada’s arid Carlin Trend.
A US$23.15 million transaction between Ridgeline Minerals and Nevada Gold Mines shows how a junior explorer can convert geological progress into cash before taking on the cost and uncertainty of mine development.
Ridgeline reported that Nevada Gold Mines, the Barrick-Newmont joint venture, acquired 100% of the company’s interests in the Swift, Black Ridge, Bell Creek and Atlas exploration projects across Nevada’s Carlin and Cortez trends. The all-cash transaction was completed effective Aug. 3, according to Ridgeline’s Newsfile release.
The release also said the transaction remained subject to final approval from the TSX Venture Exchange. That distinction matters: Ridgeline described the sale as completed and the cash payment as made on closing, but the exchange-approval condition remained part of the formal disclosure.
For gold mining news in 2026, the deal is notable less because it creates immediate production and more because it offers a clear case study in exploration monetization. Ridgeline has crystallized value from four projects while retaining exposure to its flagship Selena discovery and other Nevada assets.
The transaction in numbers
Ridgeline said the US$23.15 million payment equated to approximately C$32.7 million, based on an exchange rate of US$1 to C$1.413. Company President and CEO Chad Peters said the consideration represented a 26% premium to Ridgeline’s 20-day volume-weighted average price and a return on invested capital of more than 350% across the four projects.
| Transaction metric | Disclosed detail | Why it matters |
|---|---|---|
| Buyer | Nevada Gold Mines, a Barrick-Newmont joint venture | Gives a major Nevada operator control of the acquired exploration package |
| Assets sold | Swift, Black Ridge, Bell Creek and Atlas | Consolidates four projects across the Carlin and Cortez trends |
| Purchase price | US$23.15 million all cash | Removes financing and market-price exposure tied to the sale consideration |
| Canadian-dollar value | Approximately C$32.7 million | Provides a direct measure of the transaction’s treasury impact |
| Premium | 26% to Ridgeline’s 20-day VWAP | Indicates the negotiated value exceeded the company’s recent trading reference |
| Retained treasury | Approximately C$33 million cash and C$3 million in marketable securities | Leaves Ridgeline with significant liquidity after closing |
| Retained exploration exposure | Selena, Big Blue, Coyote and other interests | Preserves future discovery exposure beyond the sold assets |
The cash figure is approximately C$33 million after the transaction, while the securities component consists of about C$3 million in marketable securities, including shares of Spartan Metals, according to the company.
That balance-sheet outcome changes the profile of a typical junior explorer. Instead of raising capital primarily to fund each drilling campaign, Ridgeline can use transaction proceeds to advance its remaining portfolio, pursue new claims and partnerships, or evaluate other capital-allocation options. Those are management plans, not guaranteed outcomes.
What Ridgeline sold : and what Nevada Gold Mines bought
The four projects were not presented as producing mines or defined economic resources. They were exploration assets at different stages of geological advancement.
Swift and Black Ridge were held through earn-in arrangements, while Bell Creek and Atlas were owned projects. Together, they gave Nevada Gold Mines additional ground and geological targets in two of the most closely watched gold belts in the United States.
The strategic value for NGM is control. A major producer can decide how to sequence drilling, integrate geological datasets, test extensions and compare targets against existing infrastructure and regional operations. That option value is difficult for a small explorer to finance independently, particularly when projects require multiple rounds of drilling before a resource can be defined.
Ridgeline’s reported exploration results helped reduce some of that early uncertainty. At Swift, the company previously reported high-grade intercepts, including 2.7 meters grading 7.0 grams per tonne gold and a 1.1-meter interval grading 10.4 grams per tonne gold. Such results do not establish continuity, mineability or project economics, but they can provide the geological evidence needed to attract a larger counterparty.
The transaction therefore transfers the next layer of risk to NGM. Nevada Gold Mines will assume responsibility for determining whether the projects warrant additional drilling, resource definition, permitting work or eventual development studies.
The sale itself does not prove that any of the four projects will become mines. Nor does the purchase price establish a reserve, resource or net present value. It is the value of negotiated exploration interests at a particular point in time.
The value Ridgeline retained

Geologists log drill core from a Nevada exploration program.
The most important retained asset is Selena, a polymetallic carbonate replacement deposit project being advanced under a US$20 million earn-in agreement with South32.
Ridgeline said it retained its interest in the Selena agreement, including the Chinchilla Sulfide discovery. It also retained a 97-square-kilometer Nevada exploration portfolio across three projects, alongside its interests in Big Blue, Coyote and a 1% net smelter return royalty on the Eagle tungsten project.
Selena gives the company a different type of exposure from the assets sold to NGM. The project is focused on a polymetallic system containing zinc, silver, gold and copper, rather than a pure gold exploration thesis. Ridgeline has reported high-grade sulfide results at Chinchilla, as well as an exploration target for the Chinchilla Oxide deposit.
South32’s earn-in structure is also significant. Partner-funded exploration can reduce the amount of capital Ridgeline must contribute while allowing it to maintain exposure to future results. At the same time, third-party funding does not eliminate geological, permitting or development risk. It only changes how some of that risk is financed and shared.
The retained portfolio means the company has not exited Nevada exploration. It has sold a defined group of projects while preserving a cash-rich position and exposure to a separate discovery that remains in the exploration phase.
A prospect-generator model under scrutiny
The transaction offers a practical test of the hybrid prospect-generator model. Under that approach, a junior explorer identifies and advances targets, uses partnerships to fund portions of exploration, and seeks to monetize projects before it must finance the full development cycle.
That model can be attractive in a market where capital is available for discovery but more selective for construction-stage projects. A junior may be able to create value with staking, mapping, geophysics and targeted drilling, while a major producer brings deeper capital, permitting experience, technical staff and regional infrastructure.
The trade-off is that the junior gives up some or all of the long-term upside in the assets it sells. If Nevada Gold Mines later makes a major discovery at Swift, Atlas, Black Ridge or Bell Creek, Ridgeline would no longer own that direct project exposure. Its return is the negotiated sale price, not the eventual mine value.
This is the central discipline of exploration monetization: securing a price today in exchange for transferring uncertain future upside.
Scenario framework for juniors and producers
| Scenario | Potential outcome | Key question for decision-makers |
|---|---|---|
| Base case | Ridgeline deploys its cash and securities carefully while South32 funds Selena exploration | Can management create new discovery exposure without excessive dilution or acquisition risk? |
| Upside case | NGM identifies economic continuity or strategic extensions across the acquired projects | Does the transaction validate the junior’s targeting and partnership model across Nevada? |
| Downside case | Follow-up drilling fails to support continuity, or retained projects consume capital without a new discovery | Can the company preserve treasury value and maintain exploration momentum? |
| Producer case | NGM uses regional control to prioritize the strongest targets and integrate them with its Nevada pipeline | Does consolidation improve exploration efficiency and shorten the path from target to resource? |
For junior explorers, the lesson is not that every discovery should be sold. The more specific takeaway is that a sale can be a rational endpoint when the cash value materially improves financial resilience and the company retains meaningful exposure to other high-impact assets.
For major producers, the deal illustrates the value of maintaining access to Nevada’s exploration ecosystem. Early-stage projects may be too small or too uncertain to justify a producer’s full operating attention at first. Once a junior has generated enough evidence, however, the major can acquire control and decide whether the geological signal merits a larger program.
What investors should separate
The Ridgeline transaction contains three different propositions that should not be blended.
First, the cash sale is a completed corporate event as described in the company’s disclosure, subject to the stated exchange-approval condition. Second, the retained treasury is a current balance-sheet fact reported by Ridgeline. Third, Selena, Big Blue, Coyote and future Nevada targets represent exploration upside that remains uncertain.
That separation is important for evaluating both junior explorers and major producers. A completed transaction can reduce financial risk without proving future exploration success. A strong treasury can extend a company’s runway without guaranteeing value creation. A partner-funded drill program can improve capital efficiency without removing geological risk.
Ridgeline’s sale to Nevada Gold Mines is therefore best read as a case study in capital recycling. The company converted four exploration positions into approximately C$33 million of cash, retained about C$3 million in securities and kept direct exposure to a separate Nevada portfolio. Nevada Gold Mines, meanwhile, gained control of a package of projects along established gold trends where additional drilling may reveal whether early exploration signals can become resources.
The broader implication for gold mining news in 2026 is that discovery risk remains monetizable when geology, location, counterparties and transaction structure align. But the sale price marks the value of the transaction that closed : not the value of the discoveries that may or may not follow.