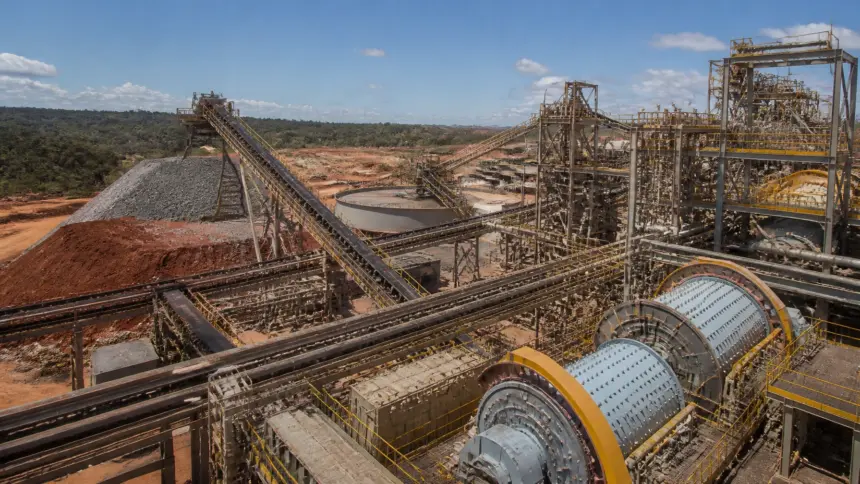
Chapada’s processing and mine infrastructure in Goiás, Brazil.
Lundin Mining’s plan to integrate the Saúva copper-gold deposit with its Chapada mine in Goiás is becoming a material brownfield growth case rather than a distant exploration option.
The proposed expansion combines a satellite deposit located approximately 15 kilometres from Chapada with an additional ball mill at the existing processing plant. Lundin expects the project to add about 15,000 tonnes of copper and 45,000 ounces of gold annually, while improving copper and gold recoveries by approximately 5%.
The timing matters for the copper market. Forecasts for 2026 remain divided between a modest surplus and a structurally tight market, with institutional price expectations broadly spanning $10,000 to $15,000 per tonne. In that environment, an expansion that uses existing roads, power, processing and export infrastructure can offer a different risk profile from a greenfield mine.
Saúva is not yet a fully permitted, independently reported mine development. Lundin’s current disclosures describe ongoing engineering, permitting and technical work. The project’s value therefore depends on three linked questions:
- Can Saúva deliver the expected grade and metallurgical performance?
- Can Chapada’s mill expansion be completed on schedule?
- Will copper prices remain high enough to support the capital and operating case through construction and ramp-up?
Chapada’s operating base
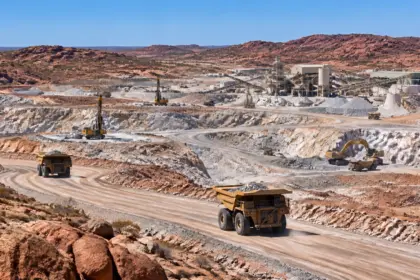
Chapada is a 100%-owned open-pit copper-gold mine in northern Goiás, approximately 320 kilometres north of Goiânia and 270 kilometres northwest of Brasília. The operation uses conventional truck-and-shovel mining, in-pit crushing and a processing plant with current capacity of approximately 65,000 tonnes of ore per day.
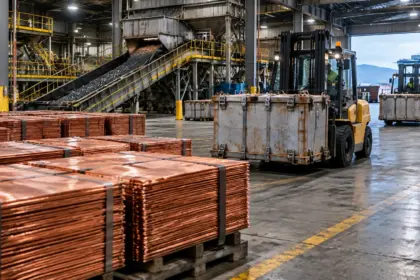
The mine produces a gold-rich copper concentrate through crushing, grinding and flotation. Concentrate is trucked to the Port of Açu for export to international smelters.
That existing logistics chain is central to the Saúva case. The proposed project would not require a new standalone concentrator or a new export route. Saúva ore would be transported to Chapada, processed through the expanded plant and moved through the established concentrate route.
Lundin reported 43,974 tonnes of copper and 61,331 ounces of gold from Chapada in 2025. Its 2026 guidance calls for 45,000–50,000 tonnes of copper and 57,000–62,000 ounces of gold.
Through the first half of 2026, Chapada produced 22,559 tonnes of copper and 29,382 ounces of gold. Payable copper sales reached 21,454 tonnes, while gold sales totaled 26,388 ounces.
| Chapada operating indicator | 2025 actual | 2026 guidance | H1 2026 |
|---|---|---|---|
| Copper production | 43,974 t | 45,000–50,000 t | 22,559 t |
| Gold production | 61,331 oz | 57,000–62,000 oz | 29,382 oz |
| Payable copper sales | Not stated in source | Not stated in source | 21,454 t |
| Processing capacity | Approximately 65,000 t/day | Existing plant plus planned mill | Existing plant |
| Copper cash-cost guidance | : | $0.75–$0.95/lb revised | $0.54/lb H1 cash cost |
Cash-cost figures are non-GAAP measures and are not directly comparable with all mining companies. Chapada’s large gold by-product credit is an important reason its reported copper cash costs are low.
Saúva’s role in the expansion
Saúva was identified as a copper-gold mineralized system approximately 15 kilometres north of Chapada. Early drilling outlined disseminated and vein-hosted copper-gold mineralization associated with bornite and chalcopyrite. The company has continued drilling to define higher-grade resources and potential down-dip extensions.
Lundin’s 2026 disclosures describe Saúva as a near-mine growth opportunity. The project is expected to replace some lower-grade Chapada open-pit feed with higher-grade Saúva ore.
The proposed production contribution is approximately:
- 15,000 tonnes of copper per year
- 45,000 ounces of gold per year
- Approximately 5% higher copper and gold recoveries from the additional grinding capacity
Those figures are project expectations, not current production. They should not be treated as a reserve-backed production forecast until the updated technical work is complete.
The project also remains subject to permitting, final design, construction execution and metallurgical performance. Lundin has indicated that an updated technical report covering Chapada and Saúva is expected in the fourth quarter of 2026.
Timeline and capital signals
The brownfield schedule has moved into physical construction preparation.
Lundin reported that:
- Earthworks for the additional ball mill began in July 2026
- Ball mill construction is expected to commence by year-end 2026
- Commissioning is targeted for late 2027
- First Saúva ore is expected in the company’s broader development target around early 2029
- Annual expansionary capital guidance increased by $35 million, from $50 million to $85 million, partly reflecting the Chapada mill project
The company’s total 2026 capital guidance includes $100 million of sustaining capital at Chapada. That budget covers ongoing mine and infrastructure requirements and is distinct from the expansionary spending associated with Saúva.
The timing creates a relatively long gap between mill construction and the expected contribution from Saúva. That gap may be necessary for mine development, permitting, road and site infrastructure, pre-stripping and commissioning activities. It also means investors and operators will have to monitor execution milestones before the project can be judged on production results.

Grinding equipment is the central processing addition in Lundin’s Saúva integration plan.
Copper price scenarios for the Saúva case
The 2026 copper outlook remains highly sensitive to concentrate availability, refined production, scrap supply, inventories and global industrial demand.
S&P Global Market Intelligence has pointed to an average copper price near $12,100 per tonne, supported mainly by supply tightness rather than unusually strong demand growth. Goldman Sachs has outlined a more cautious framework in which a market surplus could keep prices closer to $10,000–$11,000 per tonne. Other bank and analyst scenarios extend above $13,000 per tonne if mine disruptions and low inventories create a sustained deficit.
The following framework is not a valuation model or investment recommendation. It shows how different copper-price environments could affect the operational importance of Saúva.
| Scenario | Indicative 2026 copper price | Market conditions | Implications for Chapada-Saúva |
|---|---|---|---|
| Bear | $10,000–$10,800/t | Surplus, stronger scrap response, weaker industrial demand | Greater focus on construction discipline, cost control and schedule protection |
| Base | $11,000–$12,500/t | Near-balanced market with recurring concentrate tightness | Supports the case for higher-grade feed and recovery improvements |
| Bull | $13,000–$15,000/t peak range | Deficit, low inventories and supply disruptions | Increases the value of incremental copper and accelerates the payback potential of mill investment |
The project is also exposed to gold. At the planned contribution of 45,000 ounces per year, gold would remain a significant by-product credit for Chapada. Higher gold prices could reduce reported copper cash costs, while lower gold prices would reduce that offset even if copper prices remained firm.
Operational implications
1. Higher-grade feed could improve plant economics
Replacing lower-grade open-pit material with higher-grade Saúva ore could improve contained metal production without requiring an entirely new processing complex. The additional ball mill is intended to create the grinding capacity needed for that change in feed profile.
The key operational measure will be whether higher grades translate into sustained payable production. Ore hardness, mineralogy, recovery response and blending requirements will determine how much of the planned uplift is realized.
2. The 15-kilometre haul route becomes strategically important
Saúva’s proximity to Chapada is an advantage, but it does not eliminate logistics risk. The project will require a reliable haulage route, suitable road capacity, fleet availability, maintenance planning and careful traffic management.
The shorter distance should be viewed relative to a greenfield development, not as a cost-free connection. Fuel, tires, road maintenance, wet-season disruption and potential community impacts remain relevant operating variables.
3. Existing export infrastructure lowers development complexity
Chapada concentrate is already trucked to Açu for export to international smelters. No shipment tonnage for the Saúva project has been disclosed, but the future concentrate stream is expected to use the same broad mine-to-port route.
This reduces the need to establish a new export chain. However, higher concentrate production could increase truck movements, storage requirements, port handling needs and exposure to ocean freight and treatment charges.

Chapada’s existing road and export infrastructure is part of the brownfield advantage.
4. Permitting and technical disclosure remain gating items
The most important near-term milestones are not only construction-related. Saúva permitting, resource definition, metallurgical confirmation and the updated technical report will determine how much confidence can be placed in the production estimates.
The public disclosure reviewed for this analysis describes Saúva through internal studies and project updates. Until a more complete technical report is available, the 15,000-tonne copper and 45,000-ounce gold figures should be treated as forward-looking project targets rather than established production guidance.
5. Brownfield growth does not remove execution risk
Brownfield expansions typically benefit from existing infrastructure, workforce knowledge and operating data. They can also introduce interference with an operating mine.
The additional mill must be built while Chapada continues to mine and process ore. Shutdown planning, tie-ins, commissioning, power availability and mill ramp-up could affect production during the transition. Any delay could widen the gap between capital spending and Saúva’s first contribution.
What to watch next
For operators, investors and policymakers following the project, the most useful indicators will be:
- Completion and publication of the updated Chapada-Saúva technical report
- Progress on permitting and environmental approvals
- Additional drilling results and resource definition
- Final mill design, procurement and construction progress
- Evidence of Saúva’s metallurgical recovery performance
- Road and haulage infrastructure requirements
- Changes to Chapada production guidance and cash-cost assumptions
- Copper concentrate treatment charges, shipping costs and Port of Açu capacity
- The timing and conditions attached to first ore from Saúva

Exploration and drilling remain important to defining Saúva’s mine plan and production confidence.
Bottom line
Lundin’s Chapada-Saúva plan is a relatively compact copper-gold growth project with a clear brownfield logic: move ore from a nearby deposit into an existing concentrator, add grinding capacity and use an established concentrate export route.
At current guidance, Chapada is expected to produce 45,000–50,000 tonnes of copper in 2026. Saúva’s targeted 15,000-tonne annual contribution would therefore be material to the operation, particularly if the project also improves recoveries and extends access to higher-grade feed.
The copper-price outlook strengthens the strategic rationale, but it does not remove the main risks. The project remains dependent on permitting, technical disclosure, construction execution, haulage performance and the conversion of exploration results into a reliable operating plan.
For a broader view of copper supply-chain constraints, see Skillings’ analysis of copper supply, infrastructure and regional operating limits. Related coverage of mining finance and project capital costs provides additional context for brownfield development decisions.
Social snippets
LinkedIn:
Lundin Mining’s Saúva deposit could add about 15,000 tonnes of copper and 45,000 ounces of gold annually to Brazil’s Chapada mine. The brownfield plan relies on a new ball mill, existing processing infrastructure and the established route to Port of Açu. Our analysis examines the 2026 copper-price scenarios, project timeline and operational risks.
X:
Lundin Mining is advancing Saúva as a brownfield expansion of Brazil’s Chapada mine. The plan targets +15ktpa copper and +45kozpa gold, with mill commissioning targeted for late 2027. Key risks: permitting, metallurgy, haulage and copper-price volatility.
Sources
- Lundin Mining: Chapada operation, production, infrastructure and 2026 guidance
- Lundin Mining: Second-quarter 2026 results and Saúva growth update
- Lundin Mining: 2025 production results and 2026 guidance
- Lundin Mining: Saúva discovery announcement
- Lundin Mining: Chapada technical report
- Goldman Sachs: Copper price outlook and 2026 surplus scenario
- J.P. Morgan: Copper market outlook
- IEA: Copper prices and pressure on smelters