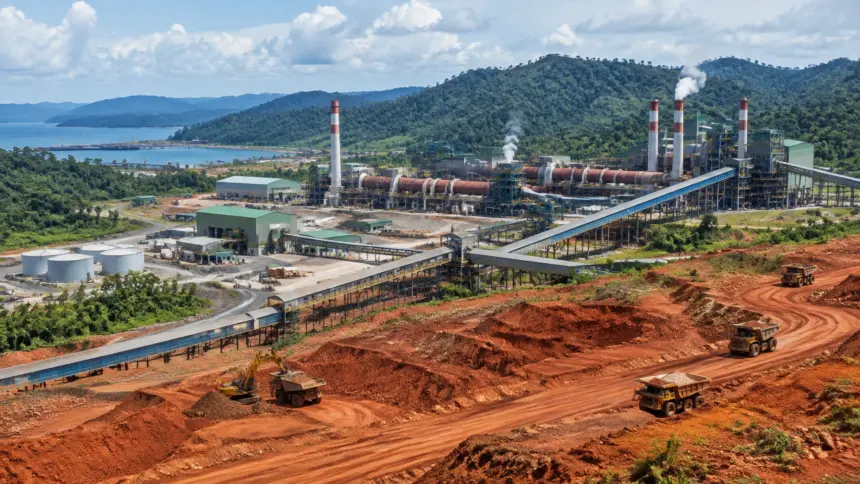
Indonesian nickel laterite mine and ferronickel processing complex.
Indonesia’s decision to tighten nickel mining approvals has changed the market’s central question. The issue is no longer whether the country has enough ore in the ground, but how much can reach smelters under the annual RKAB quota system, and at what pace.
The policy shift has narrowed the supply cushion behind the global nickel market. Indonesia’s initial 2026 quota signal was reported at roughly 250 million to 260 million wet metric tonnes, while subsequent approvals have been reported closer to 260 million to 270 million wet tonnes. Both ranges remain well below the 379 million tonnes approved in 2025.
That reduction is significant because Indonesia is the dominant source of mined nickel and a major producer of nickel pig iron, ferronickel, matte and mixed hydroxide precipitate. It has also placed a conditional floor under prices near LME cash nickel of $16,700 per tonne.
The floor is not absolute. Refined inventories remain elevated, battery demand is shifting toward nickel-free chemistries, and global stainless steel consumption is uneven. But the market is now more exposed to quota delays, ore-grade declines, smelter utilization cuts and policy revisions.
Two forecasts, one decisive variable
The most visible disagreement in the 2026 outlook is between the International Nickel Study Group (INSG) and Sumitomo Metal Mining.
INSG’s April market assessment projects global primary nickel production of 3.715 million tonnes and usage of 3.747 million tonnes, implying a 32,000-tonne deficit. That would represent a sharp change from the group’s estimated surplus of 283,000 tonnes in 2025.
Sumitomo, by contrast, sees production of approximately 3.78 million tonnes against demand of 3.52 million tonnes, producing a 256,000-tonne surplus. The difference is not a minor statistical variation. It represents a swing of almost 290,000 tonnes between a small deficit and a sizeable surplus.
The main variable is Indonesian supply. If lower RKAB approvals translate into reduced ore availability and slower refined output, INSG’s deficit scenario becomes more plausible. If supplementary quotas are released, Philippine ore imports increase and Indonesian smelters maintain high utilization, Sumitomo’s surplus case remains intact.
Nickel market balance and price indicators
| Indicator | Tighter-market signal | Surplus-market signal | Why it matters |
|---|---|---|---|
| INSG 2026 primary nickel balance | 32,000-tonne deficit | : | Assumes Indonesian supply falls faster than demand |
| Sumitomo 2026 balance | : | 256,000-tonne surplus | Assumes continued Indonesian NPI and refined growth |
| Indonesia 2025 RKAB quota | : | 379 Mt | Benchmark for the previous, less-constrained system |
| Indonesia 2026 RKAB range | 250–260 Mt initial signal; 260–270 Mt later reported range | : | Establishes a lower supply ceiling |
| Indonesian ore demand | About 312 Mt | : | Mysteel estimate based on product output, grade and recovery |
| Potential ore gap before supplements and imports | About 30 Mt | : | Based on 260–270 Mt base quota plus about 20 Mt of imports |
| LME inventory benchmark | : | About 255 kt at end-2025 in ING’s cited series | Elevated stocks limit the speed of a sustained rally |
| LME cash reference | Near $16,700/t | : | Current market level around which policy risk is being priced |
| Published 2026 price anchors | $16,600/t BMI estimate | $15,250/t ING estimate | Shows the range between firmer and surplus-based views |
Sources: INSG, Sumitomo Metal Mining reporting, Mysteel, and ING Research. Figures are not directly comparable across mined ore, refined nickel and nickel units.
Why the ore market is tighter than the metal balance
Mysteel estimates Indonesian nickel ore demand at approximately 312 million wet metric tonnes in 2026. That estimate is important because ore consumption is rising even as Indonesian nickel metal output is expected to decline.
The reason is declining ore quality. Mysteel estimates that average feed grades for some pyrometallurgical operations have fallen from about 1.55% to roughly 1.45%, while some hydrometallurgical feed has moved toward the 1.0% to 1.2% range. Lower grades require more wet tonnes to produce the same amount of nickel.
On a static basis, a 260 million- to 270 million-tonne quota combined with approximately 20 million tonnes of Philippine imports would provide 280 million to 290 million tonnes of supply. That leaves a potential gap of around 30 million tonnes against estimated demand before supplementary RKAB approvals are included.
If additional approvals lift total supply toward 305 million to 320 million tonnes, the annual balance could be broadly covered. But Mysteel argues that a stable operating system requires more than a mathematical match between supply and demand. Weather, transport delays, mine variability and timing mismatches mean that effective supply likely needs to exceed consumption by 5% to 10%.
That points to a practical requirement above 330 million tonnes for a comfortable market. On that basis, even a fully implemented supplementary quota system may leave Indonesian smelters operating with limited redundancy.

Ore grade, stockpile levels and delivery timing are becoming as important as the headline national quota.
The price floor is policy-driven, not shortage-driven
The distinction between ore tightness and refined surplus explains why nickel prices can find support without entering a classic shortage cycle.
Indonesia’s annual RKAB system limits the amount of ore that can be mined, but the global market still has refined inventories and intermediate products available. LME stocks, according to the inventory series cited by ING, had climbed to roughly 255,000 tonnes by the end of 2025, the highest level in more than four years.
That inventory acts as a ceiling on price acceleration. It gives consumers and traders a buffer while the physical ore market adjusts. It also means that a reduction in Indonesian ore supply does not immediately create a shortage of deliverable Class 1 nickel.
At the same time, the quota system raises the marginal cost and operational risk of producing nickel in Indonesia. Smelters may need to compete for specific grades, draw down stockpiles or accept lower utilization. Those costs can support LME prices even if the headline global balance remains in surplus.
The result is a market that may trade in a broad range rather than move directly into a sustained bull cycle. ING’s estimate of an average 2026 price near $15,250 per tonne reflects the drag from inventory and surplus. BMI’s estimate near $16,600 per tonne gives more weight to Indonesian supply discipline. A tighter market could push prices toward the high-$17,000s, but that would likely require visible inventory draws or a sustained reduction in refined output.
European stainless steel adds a structural risk
The European Commission’s scrutiny of MMG’s proposed purchase of Anglo American’s Brazilian nickel assets adds a separate dimension to the outlook.
The transaction, valued at about $500 million, would give MMG control of a Brazilian ferronickel business supplying material relevant to stainless steel production. The Commission has raised concerns that the deal could affect the availability, pricing or quality of ferronickel supplied to European customers.
As reported by MINING.COM, the review reflects broader European concerns about secure access to strategic raw materials and the concentration of supply chains under Chinese ownership or control.
This is not, by itself, a major change to the global nickel balance. It is more consequential for European stainless steel producers that require predictable regional supply and contract certainty. If the transaction is approved with stringent commitments, including long-term supply arrangements, the physical impact may be limited. If it is delayed, blocked or heavily conditioned, European buyers could face fewer options for ferronickel procurement.
That makes the deal a demand-side and regional supply factor rather than a direct substitute for Indonesian ore policy. European stainless producers may respond by increasing inventories, seeking alternative suppliers or adjusting procurement formulas. Any resulting premium would be regional, but it could add to volatility in a market already sensitive to policy headlines.

Ferronickel capacity remains exposed to both ore availability and regional procurement risk.
Base, bull and bear cases
Base case: a supported trading range
The base case is a market that remains technically surplus but operationally tighter. Supplementary RKAB quotas are released selectively, Philippine imports provide some relief and Indonesian smelters continue operating, though not at full capacity.
Under this scenario, nickel remains broadly range-bound around the mid-$16,000s per tonne. Ore premiums and smelter margins move higher, while refined inventories decline only gradually. This is the most consistent outcome with the competing forecasts from INSG, Sumitomo, Mysteel and ING.
Bull case: quota discipline becomes a refined deficit
The bull case requires more than a low headline quota. Supplementary approvals would need to fall short, lower grades would need to persist and smelter curtailments would need to reduce refined output. A disruption to Philippine imports or a further delay in Indonesian projects would increase the pressure.
If those conditions coincide with stronger stainless steel demand, INSG’s 32,000-tonne deficit could become the starting point for a tighter balance. LME inventories would need to draw down for prices to sustain a move toward $17,800-$18,000 per tonne.
Bear case: supply flexibility overwhelms quota discipline
The bear case emerges if Indonesia approves enough supplementary material to restore smelter feed, imports rise and product output remains resilient. Existing LME stocks would then continue to absorb surplus Class 1 metal.
Battery substitution toward lithium-iron-phosphate chemistries and weak manufacturing demand would reinforce the downside. In that environment, prices could gravitate back toward the lower end of institutional forecasts near $15,000 per tonne, despite periodic spikes caused by RKAB uncertainty.
What decision-makers should monitor
For miners, smelters, stainless producers and investors, the most useful indicators are operational rather than rhetorical:
- Monthly Indonesian ore production versus the approved RKAB ceiling.
- The volume and timing of supplementary quota approvals.
- Ore grades, premiums and stockpiles at Indonesian industrial parks.
- Philippine ore imports during the rainy season.
- Indonesian NPI, matte and MHP operating rates.
- LME stocks, cancelled warrants and the flow of Indonesian-origin metal.
- European ferronickel procurement and the MMG-Anglo regulatory review.
- Stainless steel output and battery chemistry trends.
The 2026 nickel market is therefore not defined by a simple shift from surplus to deficit. It is defined by a smaller margin for error. Indonesia’s RKAB quotas have made the ore market more disciplined and placed a floor under prices near current LME levels, but elevated refined inventories and uncertain demand still limit the upside.
The balance will be decided by the gap between what Indonesia authorizes, what mines actually deliver and what smelters can economically process.
Sources
- International Nickel Study Group: April market observations
- Mysteel: Indonesia’s 2026 nickel ore supply-demand balance
- Mysteel: Indonesia approves 260–270 million tonnes of nickel ore quotas
- ING Research: Nickel remains capped by surplus
- MINING.COM: MMG faces EU antitrust warning over Anglo nickel deal
- Skillings: Indonesia’s nickel quota tightens 2026 ore supply
- Skillings Mining Intelligence