By Charles Pitts
Mining investors are navigating three connected signals: copper’s retreat from a record as U.S. tariff expectations cool, a widening gap between listed-company valuations and M&A clearing prices, and renewed demand for royalty and streaming structures that reduce direct operating exposure. The market is rewarding scarce, permitted and infrastructure-backed assets, but the investment case still depends on normalized commodity prices, financing requirements and execution risk.
Market snapshot
| Commodity | Reference level | Type | Main investment read-through |
|---|---|---|---|
| Copper | ~US$14,169/t LME | Spot reference | Retreat from the record near US$14,875/t as tariff expectations cooled; COMEX stocks remain near records and the Sept. 30 Section 232 decision window is the key catalyst |
| Gold | ~US$4,316–4,330/oz | Spot reference | Fed rate-hike odds near 86%–87% create a neutral-to-bearish near-term bias; Goldman Sachs’ year-end view is about US$4,900/oz |
| Silver | ~US$63.55/oz | Spot reference | Sixth consecutive annual deficit supports the long-term case, but volatility remains elevated; base case is US$65–80/oz |
| Lithium carbonate | ~US$20,052/t in China | Spot reference | RMB140,000–185,000/t is the working base case; the Jianxiawo restart and fourth-quarter battery demand are key variables |
| Nickel | US$17,000–19,000/t | Scenario range | Indonesian ore quotas remain the principal supply and price swing factor |
| Uranium | ~US$86.60–90/lb | Spot and term-market reference | Stronger term-market conditions continue to support developers and producers with credible financing paths |
Copper’s next move will depend on whether U.S. stockpiling represents genuine end-user demand or inventory positioning ahead of potential tariffs. That distinction is central to both commodity forecasts and mining-equity valuations.
1) P/NAV metrics show a valuation gap, not an automatic bargain
Gold equities are trading near 0.6x P/NAV, or roughly a 40% discount, even with spot gold above US$4,300/oz. One reason is that many analyst models continue to use conservative long-term gold assumptions of approximately US$2,200–2,400/oz rather than current spot prices.
The discount is also visible across the development pipeline. Copper majors are generally valued around 1.1x–1.2x P/NAV, while mid-tier copper companies trade closer to 0.5x–0.8x. Gold juniors and developers sit around 0.4x–0.6x, and early-stage explorers around 0.3x–0.45x.
By contrast, royalty and streaming platforms command approximately 1.2x–2.0x P/NAV. Their premium reflects lower direct exposure to labour, energy and sustaining-capital inflation, as well as diversified participation in mine growth. Recent M&A has been clearing at roughly 0.73x deliverable NAV, providing a useful reference point for assets that are advanced enough to attract strategic buyers.
A low P/NAV should therefore be treated as an investigation trigger, not proof of undervaluation. The discount may reflect permitting, metallurgy, infrastructure, financing or jurisdictional risk. Investors should ask whether the asset can reach production and whether the company has enough capital to survive the process.
2) M&A intelligence: strategic access is commanding the premium
Recent transactions show buyers paying for more than resource size. Processing access, infrastructure, regional density and supply-chain control are increasingly important.
- Solar Industries India has made an approximately R21.8 billion, or US$1.4 billion, all-cash offer for South Africa’s Omnia Holdings. The proposed transaction would take Omnia private and delist it from the JSE and A2X, subject to shareholder and regulatory approvals. Solar’s rationale is centered on explosives, chemicals and access to African mining and industrial markets. Omnia’s transaction announcement places the offer in that broader strategic context.
- Rio Tinto’s agreement to acquire the Aurukun bauxite project in Queensland would strengthen its Cape York position near existing Weipa operations. Traditional-owner engagement and approvals remain important conditions. The deal illustrates why regional infrastructure and operating capability can justify interest in an undeveloped project, even when near-term production is not assured. Skillings’ M&A coverage provides additional context on the project’s permitting and infrastructure risks.
- Blue Moon Metals, Elmet Group and EQ Resources are associated with a reported US$150 million–US$175 million strategic investment to restart the Springer Tungsten Complex in Nevada. The strategic value extends beyond the deposit itself: Springer could contribute to a U.S. tungsten supply chain at a time when processing and geopolitical exposure are becoming central to project valuations.
- NEQSOL Holding’s acquisition of UMCC-Titanium in Ukraine reflects the same preference for control over processing and critical-minerals supply chains. In this type of transaction, jurisdictional and operational complexity must be weighed against the strategic value of domestic or regional supply.

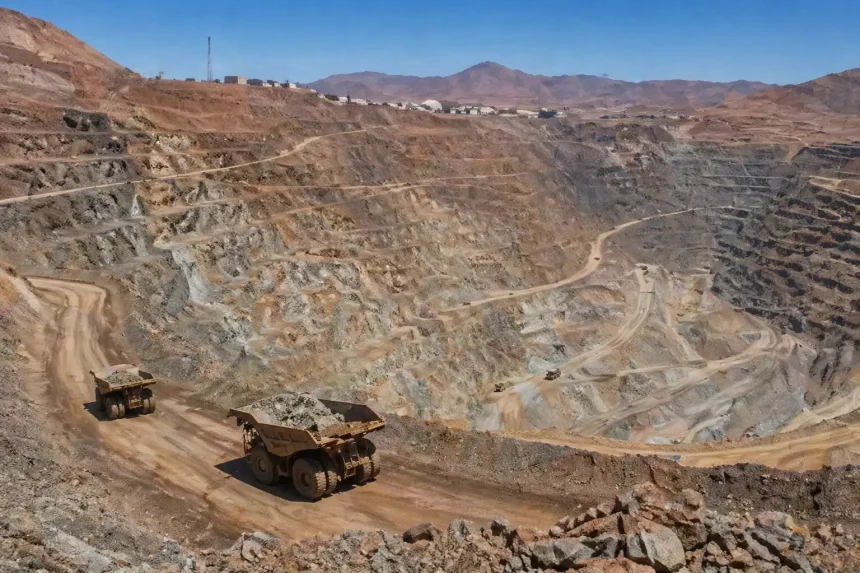
Copper cathode inventory illustrates the importance of location, deliverability and supply-chain control.
The broad investment lesson is that buyers are not simply purchasing tonnes in the ground. They are buying access to feedstock, permits, plants, skilled workforces and logistics networks that can be difficult to replicate.
3) Royalty and streaming deals reinforce the premium for flexible capital
Royalty and streaming transactions continue to attract capital because they can fund mine development without the same level of equity dilution or direct operating exposure.
Franco-Nevada agreed to pay A$170 million for an additional royalty interest in the Bullabulling Gold Project from Minerals 260. The transaction lifts Franco-Nevada’s effective interest to approximately 3.90% and forms part of a broader A$200 million follow-on financing package. The deal shows how established royalty companies can secure long-duration exposure while supporting a project developer’s funding requirements. Franco-Nevada’s investor materials and related filings provide the transaction background.
Vox Royalty has completed the acquisition of Australian gold and copper royalties covering White Dam, Kalman and Sylvania for A$8.4 million in cash. The relatively modest consideration highlights the portfolio-building model: smaller royalties can become meaningful when combined across multiple producing or advancing assets.
Mako Mining has signed a non-binding letter of intent with Sailfish Royalty for a 20-year gold purchase agreement. The proposed structure is intended to lower Mako’s cost of capital while providing Sailfish with long-term metal exposure. As with all non-binding arrangements, completion terms and financing conditions remain important.
Royalty deal evaluation checklist
Investors reviewing a royalty or streaming transaction should consider:
- Upfront cost compared with attributable production and expected mine life.
- Payback under conservative gold, silver or base-metal prices.
- Step-down provisions, buyback rights and expansion coverage.
- The operator’s balance sheet and ability to finance construction.
- Jurisdiction, permitting and political risk.
- Concentration among cornerstone assets and counterparties.
- Whether the agreement covers future discoveries or only defined resources.
The current data supports a constructive analytical bias toward royalty platforms with diversified exposure and visible counterparties. That premium is justified only when portfolio growth is broadening and the underlying operators can deliver production.
4) Commodity forecasts: separate policy positioning from consumption
Copper scenario framework
| Scenario | Indicative price range | Main assumptions |
|---|---|---|
| Bear | US$11,000–13,500/t | Tariff delay or rejection, release of U.S. stockpiles, softer Chinese demand and stronger scrap flows |
| Base | US$12,800–14,500/t | Physical tightness persists, but the policy premium moderates and inventories remain elevated |
| Bull | US$15,000–16,000/t | Tariffs are implemented, ex-U.S. inventories tighten and supply disruptions persist |
Copper’s recent rally contains both fundamental and policy-driven elements. U.S. buyers and traders have accumulated metal ahead of the Section 232 decision, but stockpiling is not the same as sustained consumption. Genuine demand would be supported by grid investment, electrification, data centers and industrial activity. Policy positioning, by contrast, can reverse rapidly if tariffs are delayed or exemptions are expanded.
A useful test is to monitor warehouse withdrawals, regional premiums, scrap availability and Chinese imports. If U.S. inventories remain locked inside the country while non-U.S. inventories decline, the tariff bull case strengthens. If stockpiled metal begins returning to the seaborne market, the price premium could narrow.
Other commodities
Gold’s near-term outlook is more balanced. With rate-hike odds around 86%–87%, higher real yields could limit momentum even while geopolitical and reserve-diversification demand support the metal. Goldman Sachs’ approximately US$4,900/oz year-end view represents a constructive longer-term case, but mining models should continue to use conservative assumptions.
Silver’s US$63.55/oz reference price is supported by a sixth consecutive annual deficit. The base case of US$65–80/oz leaves room for further gains but also implies elevated volatility, particularly for higher-cost producers and developers.
Lithium carbonate near US$20,052/t in China places the market in a recovery phase rather than a full supply-deficit cycle. The RMB140,000–185,000/t base case depends on fourth-quarter battery demand, inventory trends and the potential restart of Jianxiawo. Cost position and processing quality remain more important than headline resource size.
Nickel’s US$17,000–19,000/t range remains dominated by Indonesian ore quotas. Supply policy, rather than demand alone, will determine whether discounted nickel exposure becomes a catalyst.
Uranium near US$86.60–90/lb remains constructive, especially because term-market activity is stronger than spot. Developers with permits, offtake options and credible funding pathways are better positioned than projects relying only on spot-price momentum.
P/NAV valuation framework
| Sector | Indicative P/NAV range | Main driver |
|---|---|---|
| Royalty and streaming platforms | 1.2x–2.0x | Capital-light exposure, diversification and margin resilience |
| Copper majors | 1.1x–1.2x | Scarcity value, scale and strategic supply relevance |
| Mid-tier copper | 0.5x–0.8x | Development pathway, infrastructure and execution risk |
| Gold juniors and developers | 0.4x–0.6x | Funding needs, permitting and construction timeline |
| Early-stage explorers | 0.3x–0.45x | Discovery potential, capital access and jurisdiction |
| Recent M&A clearing level | ~0.73x deliverable NAV | Strategic control and de-risked project economics |
Investor checklist
- Test NAV using normalized, below-spot commodity prices.
- Separate stockpiling from genuine consumption in copper markets.
- Review remaining capex, dilution risk and balance-sheet runway.
- Confirm permitting, Traditional Owner or community approvals.
- Assess infrastructure, power, water, transport and processing access.
- Examine royalty burdens and offtake restrictions.
- Compare transaction value with deliverable rather than headline NAV.
- Prefer evidence of technical and construction progress over promotional milestones.