Construction MMI Falls as Steel Rebar and H-Beam Prices Dip
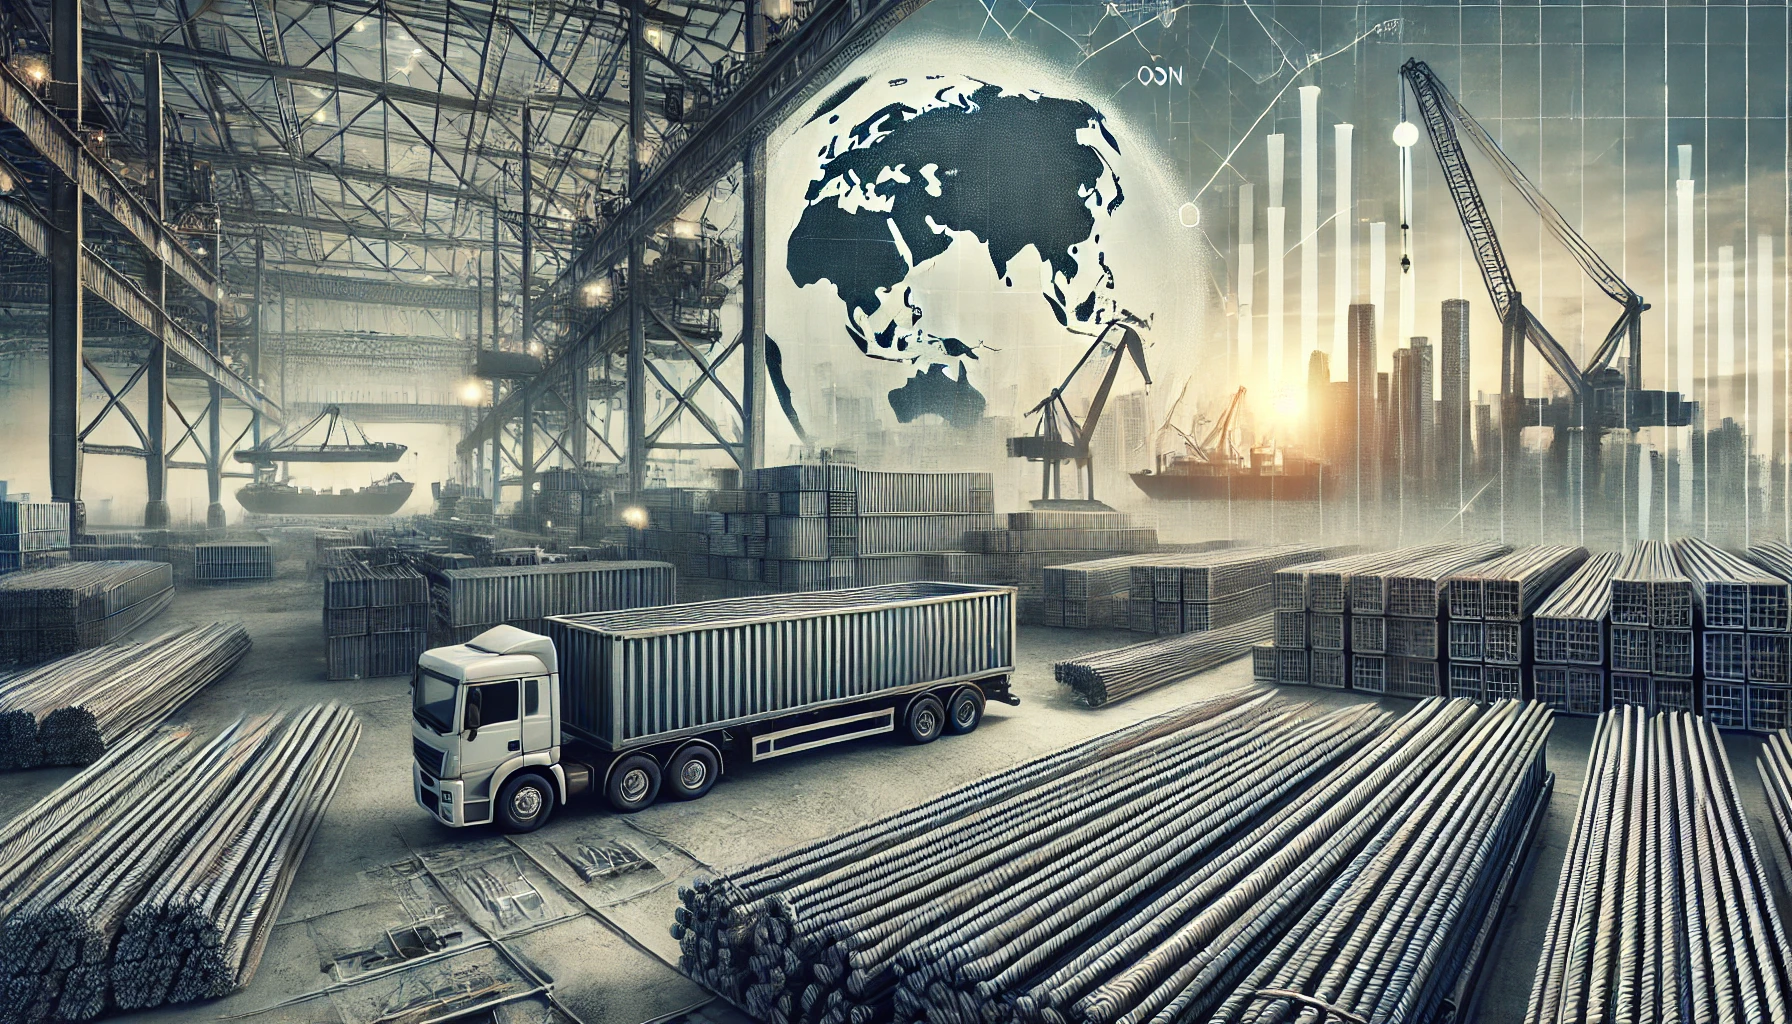
The Construction Monthly Metals Index (MMI) dropped by 3.61%, breaking out of its previous sideways trend. The decline was primarily driven by falling prices of steel rebar and h-beam steel, attributed to weak domestic demand in China. With China’s property sector showing no signs of a near-term recovery, steel prices are expected to face continued bearish pressure, impacting the global steel and construction industries.
H-Beam and Rebar Steel Prices Drop Amidst China’s Construction Slowdown
Over the past month, global steel markets have been affected by a decline in h-beam and steel rebar prices due to weak domestic demand in China. This downturn is linked to the ongoing slowdown in China’s construction sector and tighter restrictions on financing for real estate developers, creating ripple effects in steel markets worldwide.
Slowing Demand Leads to Falling Steel Prices
China’s real estate sector, a major consumer of steel, has seen a decrease in new projects as government restrictions on developer financing take a toll on the market. This has sharply reduced demand for h-beam steel and steel rebar, both critical for heavy-duty construction. Steel rebar prices in China fell by about 7% from August through early September, and ongoing weak demand has led to oversupply, impacting global markets.
Related News
- China’s Steel Crisis: A Deepening Slump Impacting the Global Iron Ore Market
- Iron Ore Price at Record High Amid Strong China Demand Outlook Raises Concerns for Steel Producers and Consumers
- Decarbonizing global iron ore and steel industry
- China steel prices show an upsurge after the covid-19 pandemic
- Steel, Iron Ore Price: Mining Group ‘Cautiously’ Optimistic On China, Global Economy
Global Impacts of China’s Steel Market Slowdown
China, responsible for over half of the world’s steel production, continues to influence global steel markets as weakened domestic demand pushes excess supply into international markets. This has resulted in downward price pressure on steel products, particularly in countries heavily reliant on steel imports, benefiting industries like real estate and infrastructure. However, this trend also poses risks of trade imbalances. Without any indication of easing financing restrictions for developers, China’s construction sector is unlikely to rebound quickly, prolonging global price volatility in steel markets.