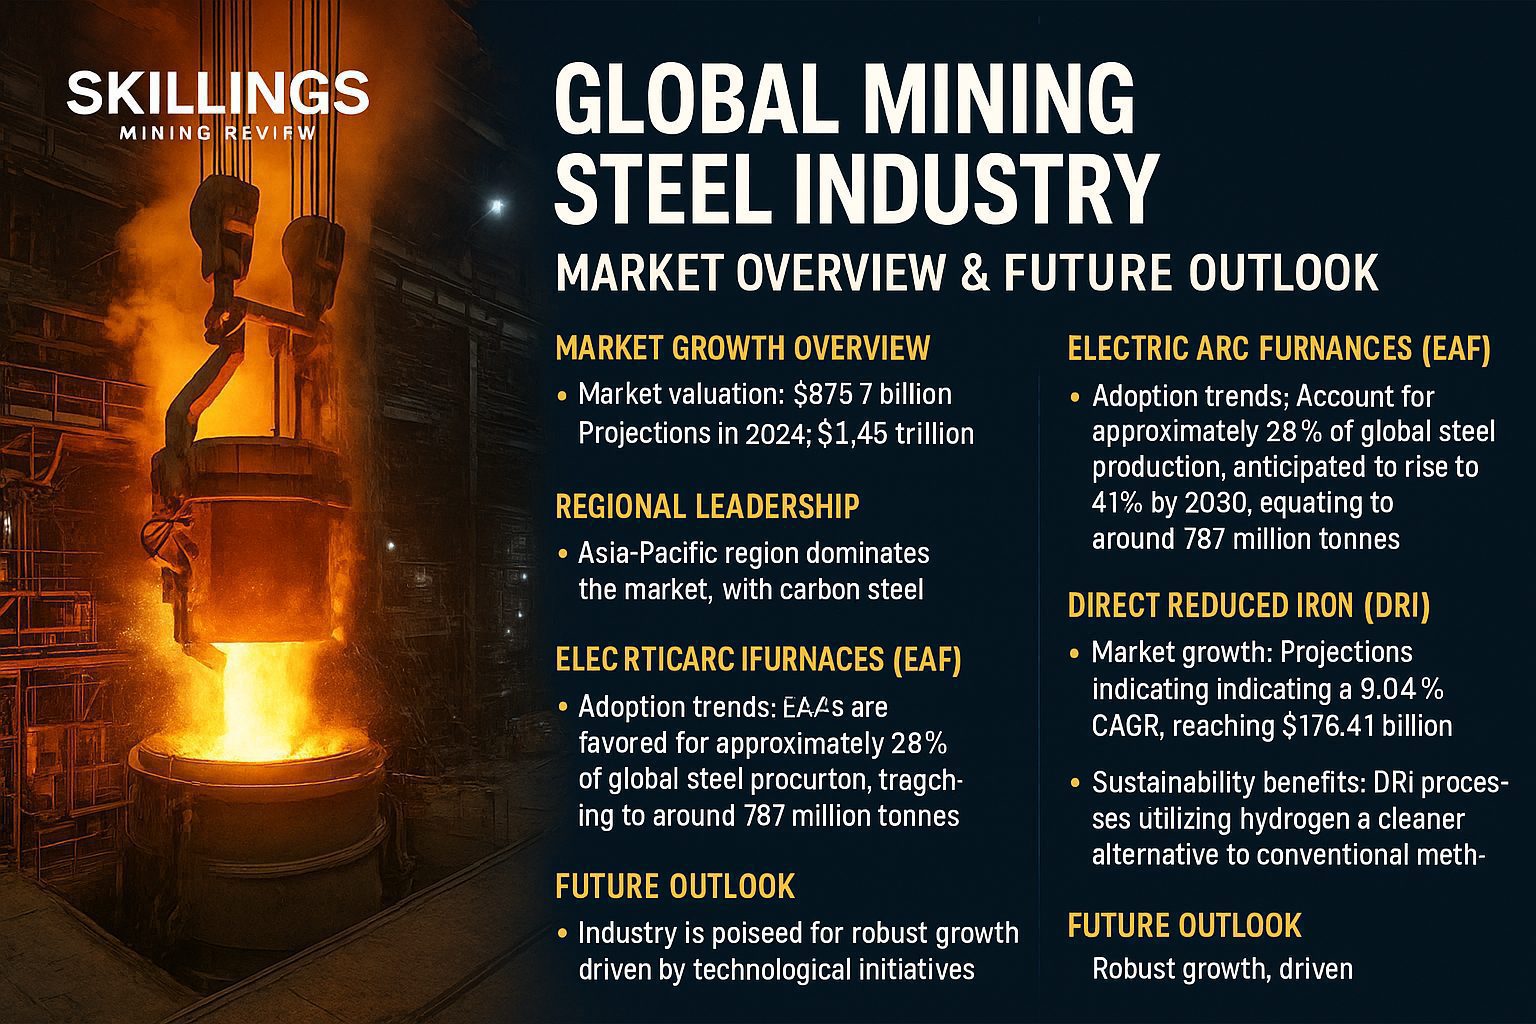
The steel mining industry is undergoing a historic transformation, fueled by surging demand from construction, automotive, and infrastructure markets—and driven increasingly by sustainable technologies such as Electric Arc Furnaces (EAF) and Direct Reduced Iron (DRI). The sector, valued at $875.7 billion in 2024, is forecast to swell to $1.45 trillion by 2035, marking a compound annual growth rate (CAGR) of 4.63%, according to BusinessWire.
Asia-Pacific Dominates as Carbon Steel Leads
At the center of this expansion is the Asia-Pacific region, where rapid urbanization and industrialization have made carbon steel the most demanded product. China, India, and Southeast Asia remain the growth engines, bolstered by large-scale infrastructure plans and automotive output. According to a report by GlobeNewswire, specialty steel is also gaining traction, particularly in tech-intensive sectors.
Related News
- Sanatana Resources Secures Gold Strike Two in Yukon Mining Project Expansion
- Peru Suspends Mining After Pataz Gold Mining Massacre Leaves 13 Dead
- Fury Gold Mines Acquisition Puts Sakami Gold Project in the Spotlight
- Adapt or Decline: The Future of Mining Organizations Is Being Forged Now
EAF Steelmaking Gains Ground
Electric Arc Furnaces, which utilize scrap steel rather than iron ore, are increasingly replacing traditional blast furnaces due to their lower carbon footprint. EAFs currently account for 28% of global steel production but are projected to rise to 41% by 2030, equivalent to 787 million tonnes, per data from Steel Hub. The technology’s scalability and eco-efficiency position it as a cornerstone of future steelmaking strategies.
While EAF adoption is accelerating in North America and Europe, challenges remain in China, where only 10% of steel came from EAFs in 2023—well short of the government’s 15% target for 2025. Limited scrap availability and entrenched blast furnace infrastructure continue to hold back adoption, according to Reuters.
DRI Market Expands with Green Steel Promise
Complementing EAFs, Direct Reduced Iron is gaining momentum as a cleaner feedstock alternative. The global DRI market is projected to reach $176.41 billion by 2034, growing at a robust CAGR of 9.04%, notes Precedence Research. Hydrogen-based DRI, still in its early stages, holds the promise of zero-carbon steel production—aligning closely with European climate mandates and private sector ESG targets.
Sweden is at the frontier of this shift, aiming to deliver the world’s first zero-emission steel by 2025. HYBRIT, a joint venture between SSAB, LKAB, and Vattenfall, is using hydrogen instead of coal in its pilot plants—a milestone tracked closely by both competitors and regulators.
Regional Moves: UK, Sweden, China
Policy is playing a pivotal role in shaping steel mining’s trajectory. In the United Kingdom, British Steel plans to add over 180 new roles after receiving state support to transition its operations toward greener technologies. Meanwhile, China’s lag in EAF adoption could have global pricing and supply implications if overcapacity persists.
Europe continues to outpace others in decarbonization, with Sweden’s early-mover advantage likely to set a benchmark for low-emission steel certification and export value.
Long-Term Outlook: Cleaner, Faster, Global
The steel mining industry stands at an inflection point. The combined force of EAF and DRI technologies, regional decarbonization policies, and end-user sector growth paints a bullish picture. However, the speed and equity of the transition will depend on raw material availability, financing mechanisms, and the ability of emerging economies to retrofit or leapfrog old technologies.
As steel becomes the next battleground in the global race for carbon neutrality, companies investing early in low-emission production and circular resource flows are expected to capture long-term margins and regulatory favor.