Lithium Supply Shock: How Zimbabwe’s Export Ban Could Redraw the Global Market

By Charles Pitts
The global lithium market reached a significant turning point on February 25, 2026, when the Zimbabwean government fast-tracked a comprehensive ban on the export of all raw lithium ore and unrefined spodumene concentrate. This wasn’t just another regulatory hurdle in a minor jurisdiction; it was a structural shift by the world’s fourth-largest hard rock lithium producer.
As of May 2026, the ripple effects are becoming visible across the supply chain. What was once a steady flow of raw material into Chinese refineries has been replaced by a mandate for local value addition. This policy shift, often referred to in industrial circles as the “Zimbabwean Gambit,” is forcing a rethink of the “geology-first” investment model, prioritizing refining corridors over simple extraction.
The Immediate Shock: China’s Squeeze
For years, Zimbabwe served as a critical satellite for China’s lithium ecosystem. Major players like Sinomine Resource Group and Zhejiang Huayou Cobalt invested billions to secure offtake from assets like Bikita Minerals and Prospect Lithium. However, the immediate nature of the February ban: which provided no transition period: left several major Chinese refineries in a precarious position.
Data from late April indicates that several “toll refining” facilities in mainland China, which rely exclusively on African spodumene, have begun to draw down their final stockpiles. The impact on lithium carbonate production is expected to be tangible by mid-May, as the logistical lead time for alternative supply from Australia or South America cannot compensate for the sudden loss of Zimbabwean tonnage.
This supply-side friction is a primary driver behind the current 2026 lithium forecast, which suggests that the narrative of a perpetual oversupply is rapidly eroding.

Lithium Price Forecast 2026: The New Baseline
The ban has introduced a floor for prices that many analysts didn’t see coming at the start of the year. While the 2023-2024 surplus suppressed the market, the removal of high-grade Zimbabwean raw ore from the spot market is tightening the spread between spodumene and chemicals.
Our current model for the remainder of 2026 identifies three distinct scenarios for lithium carbonate prices:
| Case | 2026 Forecast (LCE / Tonne) | Drivers |
|---|---|---|
| Bear Case | $14,500 | Prolonged global EV slowdown and rapid ramp-up in Argentinian brine. |
| Base Case | $18,200 | Zimbabwe’s ban holds; Chinese refineries face 8-10% supply shortfall. |
| Bull Case | $22,800 | Geopolitical escalation in South America coupled with AI-driven energy storage demand. |
Investors and operators are increasingly looking toward the 2026 Lithium Power Map to understand which regional hubs are positioned to capture the value that Zimbabwe is now forcibly keeping within its borders.
The Rise of Regional Refining Hubs
Zimbabwe’s policy is designed to capture the “refining margin”: the lucrative gap between selling raw rocks and high-purity chemicals. By mandating local processing, the government is incentivizing the construction of lithium sulphate plants.
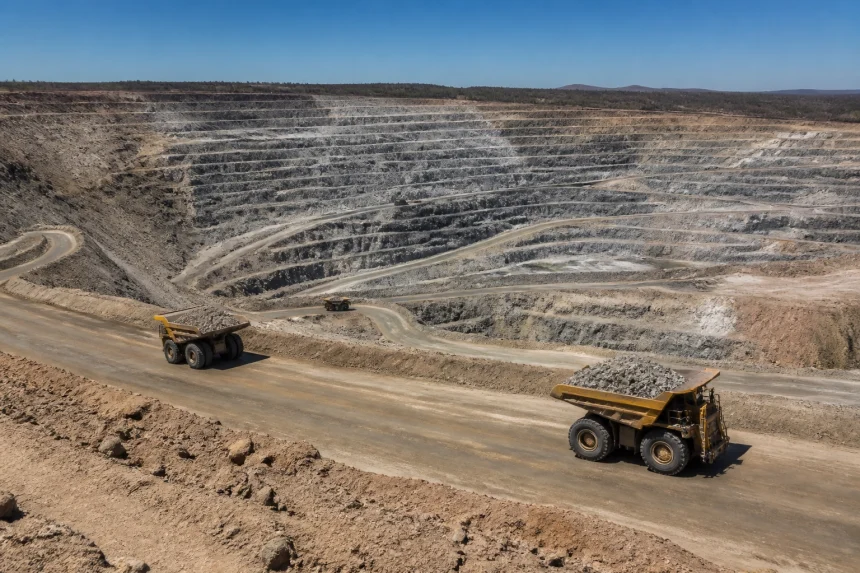
The two most advanced projects, Bikita Minerals (Sinomine) and Prospect Lithium (Zhejiang Huayou Cobalt), are currently undergoing rapid expansion to meet these new requirements. These facilities aren’t just local success stories; they represent a broader trend in mining news where resource-rich nations are no longer content with being the world’s “quarry.”
The shift to regional refining does, however, come with operational risks. Zimbabwe’s power grid remains a bottleneck. For these refining hubs to function at scale, they will require massive investments in captive renewable energy and stable grid infrastructure.

Operational Impact: A Tale of Two Tonnages
When analyzing the impact of the ban, it is crucial to distinguish between the various grades of material coming out of the country. Zimbabwe isn’t just a producer of standard spodumene; it is a major source of petalite, which is critical for specialized glass and ceramics.
| Source | Projected 2026 LCE (Tonnes) | Impact of Export Ban |
|---|---|---|
| Bikita Minerals | 65,000 | Immediate shift to onsite sulphate production. |
| Prospect Lithium | 52,000 | Accelerated phase 2 refinery construction. |
| Zulu Lithium | 12,000 | High sensitivity to transport costs; local processing essential. |
| Artisanal/Other | 15,000 | Effectively halted by lack of legal export channels. |
Source: Skillings Mining Intelligence Data (May 2026)
The ban effectively erases the “artisanal” or “illegal” export market, which had previously leaked significant tonnage into the global spot market. By consolidating production into sanctioned, large-scale industrial sites with onsite refining, Zimbabwe is bringing transparency: and pricing power: back to its borders.
Geopolitical Repercussions: The Critical Minerals Race
The move has not gone unnoticed in Washington or Brussels. As Zimbabwe leans into its partnership with Chinese state-backed firms to build this refining infrastructure, the “de-risking” strategies of Western OEMs are becoming more complicated.
Lithium remains at the heart of the critical minerals conversation. If Zimbabwe successfully transitions from a raw ore exporter to a chemical producer, it sets a precedent that other African nations, such as Mali and the DRC, are likely to follow. This “resource nationalism” 2.0 is less about seizing assets and more about seizing the value chain.

Looking Ahead: The 2027 Outlook
While the immediate impact of the ban is a tightening of supply for Chinese refineries, the medium-term outlook depends on Zimbabwe’s ability to execute its industrialization strategy. If the domestic refineries can come online with the projected 180,000 tonnes of LCE capacity by early 2027, Zimbabwe will have successfully rewritten the playbook for African mining.
For operators, the lesson is clear: geology is no longer enough. The ability to navigate local policy and invest in downstream infrastructure is now the primary differentiator in the lithium sector. As we continue to track these developments, the focus remains on the “refining map” rather than just the “resource map.”