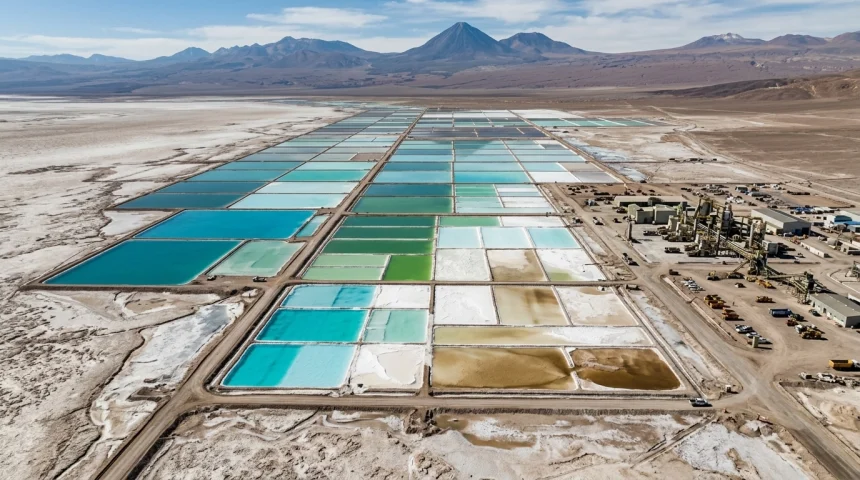
The lithium market is entering a pivotal transition phase in 2026. Following a period of aggressive oversupply and a sharp price correction throughout 2024 and 2025, the sector is now grappling with a new reality: the emergence of “mega-deposits” like the recent Hunan discovery in China, set against a backdrop of maturing electric vehicle (EV) demand.
For operators and investors, 2026 represents the “pivot year.” The market is moving from a clear glut toward a structural tightening that could define the next decade of the energy transition. Understanding the lithium price forecast 2026 requires a deep dive into how these supply surges interact with geopolitical shifts in the rare earths supply chain 2026 and beyond.
The Hunan Factor: A Strategic Shift in Domestic Supply
The discovery of a massive hard-rock lithium deposit in Hunan’s Linwu County (the Jijiaoshan mining area) has reshaped the supply narrative. Confirmed in mid-2025 and fast-tracked for licensing, the deposit is classified as an altered granite-type resource.
Official data indicates approximately 490 million metric tons of ore, containing 1.31 million tons of lithium oxide (Li₂O). When converted, this represents roughly 3.24 million tons of lithium carbonate equivalent (LCE).
Key Specs of the Jijiaoshan Discovery
| Metric | Detail |
|---|---|
| Ore Resource | ~490 million tons |
| Li₂O Grade (Avg) | ~0.268% |
| LCE Potential | ~3.24 million tons |
| Planned Annual Output | ~88,000 tons LCE |
| Status | Mining license obtained (Dec 2025) |
While the grade is lower than traditional high-grade spodumene projects, the scale of the operation: planned to mine 22 million tons of ore annually: is designed to bolster China’s domestic mineral security. For the global market, this means China is less reliant on Australian or South American imports, potentially softening the “scarcity premium” that drove prices in 2022. However, it also concentrates more of the upstream supply within the same region that dominates refining.

Lithium Price Forecast 2026: Base, Bull, and Bear Cases
As of early 2026, the consensus among major financial institutions suggests that prices have found a floor. However, the recovery is expected to be gradual rather than explosive.
1. The Base Case: Stabilization (US$13,000 – $17,000/t)
Most analysts, including Goldman Sachs and BMI, project 2026 average prices for battery-grade lithium carbonate in the mid-teens. This scenario assumes that while new supply from Hunan and Argentina enters the market, it is largely absorbed by a 12–14% CAGR in lithium-ion battery demand. This creates a “near-balanced” market by late 2026.
2. The Bull Case: The Spodumene Squeeze (US$22,000 – $26,000/t)
A bull case emerges if project delays persist in South America or if Zimbabwe’s export ban (accelerated in early 2026) creates a structural deficit in spodumene concentrates. Early 2026 spot prices have already touched the mid-US$20k range, suggesting that short-term supply-chain bottlenecks can easily override long-term averages.
3. The Bear Case: The Lepidolite Overhang (US$10,000 – $12,000/t)
If EV adoption in the US and Europe continues to lag behind aggressive targets, or if Chinese lepidolite and Hunan’s granite-hosted lithium can be produced more cheaply than anticipated, prices could remain depressed. A lower-for-longer environment would likely trigger a reset in M&A momentum and NAV valuations across the junior mining sector.
Geopolitics and the Rare Earths Supply Chain 2026
The lithium story cannot be separated from the broader rare earths supply chain 2026 landscape. Geopolitical tension remains the primary driver of volatility.
In April 2025, China imposed a strict licensing regime on several critical minerals, targeting sectors tied to defense and high-tech industries. While a temporary “minerals truce” between the U.S. and China was established in late 2025, that agreement is set to expire in November 2026.
Why the November 2026 Expiry Matters:
- Supply Shocks: If the truce is not extended, a “snap-back” of export controls could cause an immediate spike in the prices of heavy rare earths (HREEs) like dysprosium and terbium.
- Diversification Lag: Although the U.S. and Australia have committed over $1 billion to joint production, most non-Chinese processing capacity is not expected to be fully operational until 2027 or 2028.
- Resource Nationalism: We are seeing more producer states, such as Peru with its strategic pivot, declaring lithium as a national pillar, which adds layers of regulatory complexity for multinational operators.

Supply/Demand Balance: 2026 vs. 2027
On paper, 2026 remains in a “nominal surplus.” Nameplate capacity across global mines and chemical converters exceeds forecast demand. However, the “real-world” supply is much tighter.
Forecasters identify a structural deficit in spodumene (upstream) even when there is a surplus of lithium chemicals (downstream). This is due to a mismatch between mining output and converter capacity. As the wave of new project completions from the 2022-2023 investment boom crests in mid-2026, the pipeline for 2027 looks remarkably thin.
Forecast Table: Market Balance and Prices
| Year | Projected Balance | LCE Price Forecast (Avg) | Demand Growth (CAGR) |
|---|---|---|---|
| 2025 | Surplus (~40k tons) | $11,500/t | 13% |
| 2026 | Near-Balance / -1.5k ton Deficit | $15,200/t | 14% |
| 2027 | Deficit (~25k tons) | $16,800/t | 12% |
Note: Data synthesized from Goldman Sachs, BMI, and Wood Mackenzie reports.
The consensus is that by late 2026 or early 2027, the market will flip into a sustained deficit. This is driven by the fact that no large-scale lithium projects with clear production plans are scheduled to start after the second half of 2025.

Operational Takeaways for Decision-Makers
For mining executives and investors, the 2026 outlook mandates a focus on three areas:
- Cost Competitiveness: In a “stabilized” price environment of $15k-$17k/t, high-cost lepidolite and marginal brine projects will struggle. Tier-1 assets with low operating costs will be the primary beneficiaries of the 2027 deficit.
- Geopolitical De-risking: The risk of the U.S.-China truce expiring in Q4 2026 means offtake agreements should prioritize “China-light” supply chains where possible, despite the higher near-term cost.
- Technological Efficiency: As seen in the Hunan granite deposit, extracting value from lower-grade ore requires scale and advanced processing. Companies investing in autonomous haulage and advanced telemetry will be better positioned to handle the logistical complexity of these mega-sites.
The lithium market in 2026 is no longer about the wild speculative swings of the past; it is about the industrial reality of scaling the energy transition. While the Hunan discovery adds a massive new weight to the supply side, the fundamental trajectory of EV and ESS demand suggests that the current breathing room for buyers is temporary.