In the capital-intensive world of mineral extraction, the definition of “risk” is undergoing a fundamental shift. For decades, project risk was largely a calculation of grade, depth, and metallurgy. Today, the most significant threat to Net Present Value (NPV) is not the ore body, but the “Social License to Operate” (SLO).
As we move through 2026, the industry is witnessing the maturation of ESG 2.0. This is no longer a world of “nice to have” sustainability reports or glossy CSR brochures. Instead, mining ESG reporting trends have hardened into a mandatory, data-driven framework that dictates everything from insurance premiums to permitting timelines.
In this new era, social license has transitioned from an abstract concept into a tangible de-risking strategy. Companies that treat community engagement as a core operational discipline are seeing faster approvals and lower costs of capital, while those lagging are finding themselves locked out of the global energy transition.
The hardening of mining ESG reporting trends in 2026
The year 2026 marks a regulatory watershed. On January 1, GRI 14: Mining Sector 2024 officially took effect, setting a new global baseline for how companies disclose water usage, land disturbance, and biodiversity impacts. This isn’t just another checklist; it is a granular requirement for site-level transparency.
Furthermore, the convergence of IFRS Sustainability Disclosure Standards (S1 and S2) has forced ESG data into the same rigorous audit cycles as financial results. Investors are no longer looking at ESG as a separate “non-financial” metric. They are analyzing how climate transition plans and community relations affect long-term asset valuation.
| Reporting Standard | Key Focus Area in 2026 | Impact on Operators |
|---|---|---|
| GRI 14 | Water, Land, and Biodiversity | Mandatory site-level granularity. |
| IFRS S2 | Climate Transition Planning | Requires costed adaptation strategies. |
| CSRD (EU) | Supply Chain Due Diligence | Direct impact on EU market access. |
| GISTM | Tailings Management | Prerequisite for project financing. |
This “hardening” of data means that a mine’s social license is now visible on the balance sheet. A project that lacks Indigenous consent or community trust is no longer just a PR liability: it is a stranded asset risk.
Case Study: The Gold Fields/Cree Nation Partnership at Windfall
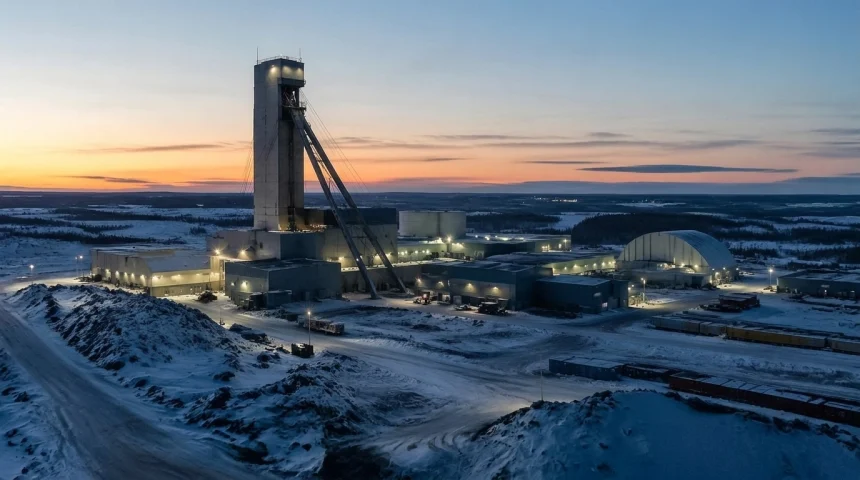
The most compelling evidence of ESG 2.0 in action is the Windfall Project in Quebec. Following its acquisition of Osisko Mining in late 2024, Gold Fields has centered its development strategy on a landmark partnership with the Cree Nation.
The centerpiece of this strategy is the 85 km, 69 kV hydroelectric power line. Unlike traditional mining infrastructure, this line was built, owned, and operated by the Cree First Nation of Waswanipi.
Why this matters for de-risking:
- Decarbonization: By connecting to the provincial grid, the Windfall project significantly reduces its reliance on diesel, slashing Scope 1 emissions.
- Economic Alignment: The Cree Nation is not just a “stakeholder” receiving a royalty; they are infrastructure owners and business partners. Their economic success is directly linked to the project’s longevity.
- Permit Stability: The signing of a “landmark” Impact and Benefit Agreement (IBA) in July 2025 with the Cree First Nation and the Grand Council of the Crees has created a stable, multi-level governance framework that minimizes the risk of legal challenges or blockades.
By integrating the Cree Nation into the project’s core infrastructure, Gold Fields has effectively converted a potential source of friction into a pillar of operational stability.

Mining permits reform 2026: The SLO fast-track
As governments globally race to secure supply chains for critical minerals, we are seeing a paradox in regulation. While many jurisdictions are attempting to streamline the path to production, they are simultaneously tightening ESG expectations.
In 2026, the concept of “Integrated Permitting” has emerged. Regulators in Canada, Australia, and the US are increasingly conditioning “fast-track” status on the demonstration of early and meaningful Indigenous consultation and robust biodiversity baselines.
The mining permits reform 2026 initiatives often feature “carve-outs” for projects that can demonstrate high ESG performance. For example, projects that have secured pre-approvals or co-management agreements with local communities are often exempt from certain redundant review cycles, potentially saving years in the development timeline.
Investor sentiment: Capital follows the license
The investment landscape for 2026 is clear: institutional capital is fleeing projects with “messy” social contexts. Large-scale institutional investors and lenders are now using nature and water risks as “hard screening filters.”
“Social license is no longer a ‘soft’ metric,” says one leading mining analyst. “If you can’t show me a clear path to community consent, I can’t model your project’s timeline with any degree of certainty. Without a predictable timeline, your NPV is a guess.”
This sentiment is driving M&A momentum toward companies that have already de-risked their social landscape. Assets like Windfall or Agnico Eagle’s Ontario operations are commanding premiums because they represent “safe harbor” investments in an increasingly volatile geopolitical climate.

Operationalizing social license: Three key pillars
To thrive in the ESG 2.0 environment, operators must move beyond compliance and toward genuine integration.
1. From Consultation to Co-Ownership
The Windfall power line model demonstrates that co-ownership is the ultimate de-risker. When host communities own the utilities, services, or even equity in the project, the incentive structure shifts from “extractive” to “collaborative.”
2. Real-Time Disclosure
With the rise of autonomous haulage and IoT-enabled mine sites, companies now have the data to provide real-time environmental monitoring to local communities. Transparency breeds trust; hidden data breeds suspicion.
3. Integrated Resilience Planning
Mining permits in 2026 now require costed adaptation measures for extreme weather and water stress. These plans should be co-designed with local communities who share the same watershed and regional climate risks.
Conclusion: The competitive advantage of ESG 2.0
The era of viewing ESG as a hurdle to be cleared is over. In 2026, social license is a competitive advantage. It is the lever that unlocks capital, secures permits, and ensures that a project can survive the geopolitical shifts of the decade.
As we look toward the 2026 outlook for critical minerals and copper, the winners will not necessarily be the companies with the highest grade, but those with the most durable social licenses. In a world hungry for minerals but sensitive to impact, being a “good neighbor” is the most sophisticated financial strategy available.