As the global race for battery-grade materials intensifies, the narrative of African lithium is shifting away from established hubs like Zimbabwe and Mali toward a new, high-potential frontier: Nigeria. Long known for its vast oil reserves and burgeoning tech sector, Nigeria is now leveraging its Precambrian basement complex to secure a seat at the table of critical mineral producers.
The stakes are high. As of mid-2026, Nigeria is no longer content with being a mere exporter of raw ore. A series of aggressive federal policy shifts, coupled with significant foreign direct investment (FDI) into local processing facilities, is transforming the country’s lithium landscape. For investors and operators, the central question is whether Nigeria can overcome its infrastructure and security hurdles to become a Tier-1 hard-rock powerhouse.
The Geological Prize: Spodumene and the Pegmatite Belt
Nigeria’s lithium potential is rooted in its extensive pegmatite belts, which stretch across states including Nasarawa, Kogi, Kaduna, Kwara, and Ekiti. Unlike the lithium brines found in the “Lithium Triangle” of South America, Nigeria’s deposits are primarily hard-rock.
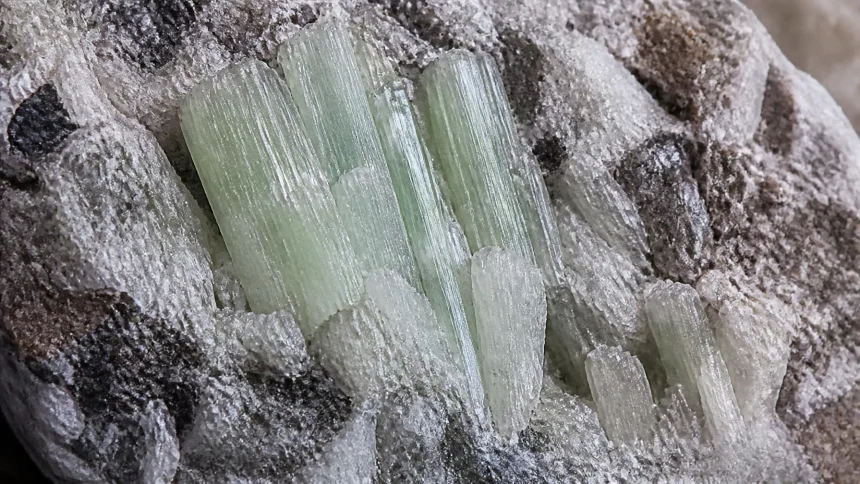
Recent geological surveys and independent testing have confirmed the presence of high-grade spodumene: the preferred feedstock for lithium hydroxide production. Reports from early-stage projects, such as those led by Chariot Corporation, have indicated Li₂O grades ranging from 2.66% to nearly 6%, positioning Nigerian ore among the most attractive globally in terms of raw purity.

While lepidolite and petalite are also present, the focus for 2026 is squarely on spodumene-bearing pegmatites. These deposits are geologically comparable to the world-class districts of Western Australia, offering a familiar technical blueprint for international mining houses. This geological foundation is a core component of the broader critical minerals outlook for 2026, where diversification away from traditional supply chains is a priority.
The Policy Lever: Nigeria’s New Mining Mandate
Perhaps the most significant driver of the current “lithium boom” in Nigeria is a pivot in federal regulation. Under the direction of President Bola Tinubu and the Ministry of Solid Minerals Development, the Nigerian government has implemented a “value-addition” mandate.
Starting in 2024 and reaching full enforcement in 2026, mining licenses for critical minerals like lithium are increasingly tied to a requirement for in-country processing. The government’s stance is clear: the era of “pit-to-port” raw ore exports is coming to an end. To secure a long-term mining lease, operators must demonstrate a commitment to building concentrators or refineries on Nigerian soil.
This policy serves two purposes. First, it aims to capture a larger share of the value chain, transitioning from selling $400/tonne raw ore to $2,500+/tonne spodumene concentrate. Second, it encourages the formalization of a sector that has historically been plagued by artisanal and unregulated activity. For investors, this shift necessitates a higher capital expenditure (CAPEX) entry point but offers greater long-term regulatory security and alignment with national industrial goals.
Key Players and Processing Milestones
The response to Nigeria’s processing mandate has been led largely by Chinese capital, though Western junior miners are beginning to establish a more visible footprint.
- Ming Xin Mineral Separation: In Kaduna State, the Kangimi processing plant: a joint venture with the Kaduna Mining Development Company (KMDC): is a flagship project. With a planned capacity to process 1,500 metric tons of ore daily, the facility represents a major leap in domestic beneficiation.
- Chariot Corporation: As one of the first ASX-listed firms to aggressively enter the Nigerian lithium space, Chariot has secured six mining licenses. Their focus on high-grade spodumene in Kwara State has made them a bellwether for Western investor sentiment in the region.
- Jiuling Lithium & Canmax Technologies: These firms have collectively committed over $800 million toward processing infrastructure, with plants scheduled to ramp up operations throughout 2026.

The rise of these projects is changing the way analysts view project valuation and P/NAV metrics for African juniors. The ability to de-risk a project through local processing and government-backed Special Purpose Vehicles (SPVs) is becoming a prerequisite for institutional backing.
Nigeria Lithium: 2026 Project & Processing Snapshot
| Project / Company | Location | Primary Mineral | Status (2026) |
|---|---|---|---|
| Kangimi Plant (Ming Xin) | Kaduna | Spodumene | Early Operations / Ramp-up |
| Kwara Lithium (Chariot) | Kwara | Spodumene | Advanced Exploration / Drilling |
| Nasarawa Hub (Jiuling) | Nasarawa | Spodumene/Lepidolite | Commissioning Phase |
| Kelechi Minerals | Various | Spodumene | Local Beneficiation / Exporting |
| Edo State SPV | Edo | Spodumene | Planning / Land Allocation |
Comparative Outlook: Nigeria vs. Regional Peers
While Nigeria’s progress is notable, it still trails the established production volumes of Zimbabwe’s Bikita and Arcadia mines or Mali’s Goulamina project. However, Nigeria’s competitive advantage lies in its geography and policy speed.
Unlike landlocked Mali, Nigerian projects benefit from closer proximity to Atlantic shipping routes, and the federal government’s rapid deployment of processing mandates has forced an infrastructure build-out that other nations are only beginning to contemplate. While the 2026 Lithium Power Map remains dominated by North American and Australian projects, the cost-curve for Nigerian hard-rock lithium is proving increasingly competitive.
Risks: Infrastructure, Security, and Volatility
The path to becoming a powerhouse is not without obstacles. Three primary risks dominate the Nigerian lithium narrative for 2026:
- Infrastructure Gaps: While processing plants are being built, the reliable power required to run them remains a challenge. Many operators are forced to invest in captive power solutions (solar or gas), adding to the operational expenditure (OPEX).
- Security: Key lithium-rich regions in Northern and Central Nigeria have faced historic challenges with armed groups and local insecurity. Protecting staff and supply chains is a non-negotiable cost of doing business.
- Price Volatility: Like all lithium producers, Nigerian projects are sensitive to global spot prices. While the 2026 outlook for lithium remains structurally sound due to the energy transition, any prolonged price dip could stall the financing of the next wave of refineries.

The Bottom Line for 2026
Nigeria is no longer a “sleeper” in the lithium market. The combination of high-grade spodumene geology and a mandatory local processing policy has created a unique environment for industrial-scale development. For mining professionals and investors, the focus for the remainder of 2026 will be on the successful commissioning of the first wave of refineries and the formalization of the upstream supply chain.
If Nigeria can successfully bridge its infrastructure gap, it won’t just be an African player: it will be a global one.