The global lithium market is navigating a period of intense technical pressure as prices for battery-grade carbonate have dipped to a five-month low, testing a critical psychological and operational floor near $18,000 per tonne. This recent slide is largely attributed to the resumption of operations at CATL’s Jianxiawo lepidolite mine in China, a development that has reignited concerns regarding a potential supply glut extending into 2027.
While the market remains focused on the immediate supply influx, a complex interplay of emerging fiscal policies and shifting demand profiles suggests that the 2026 outlook is far from a one-way bear trade. As China prepares to implement a new consumption tax on lithium-ion batteries and stationary energy storage systems (ESS) continue to decouple from the volatile electric vehicle (EV) sector, operators and investors are recalibrating their expectations for the mid-decade mineral cycle.
The Jianxiawo Catalyst and Supply Headwinds
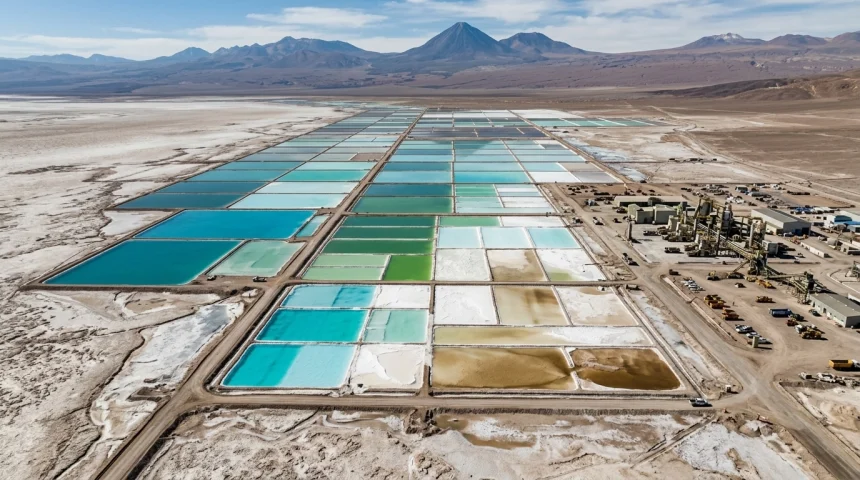
The restart of CATL’s Jianxiawo project in Jiangxi province represents a pivotal moment for domestic Chinese supply. Lepidolite, often considered a higher-cost source of lithium compared to spodumene or brine, was the first to be curtailed during the price collapses of 2024 and 2025. Its return signifies that major producers now view the $15,000–$18,000 range as a sustainable baseline for high-cost production to remain online.

However, the “restart” narrative carries significant weight beyond simple tonnage. It signals to the market that the anticipated supply-side discipline may be more fragile than expected. With several large-scale projects in Argentina and Africa also scheduled to reach nameplate capacity by late 2025, the industry is eyeing a surplus that could persist into 2027.
Analysts at Skillings Mining Intelligence note that while Jianxiawo softens near-term tightness, it does not fundamentally negate the structural demand growth anticipated for the latter half of the decade. The risk remains that over-correction in the current pricing environment could lead to further project deferrals elsewhere, creating a “boom-bust” echo that could tighten the market prematurely in late 2026.
Policy Shocks: China’s September 2026 Battery Tax
A critical variable often overlooked in current modeling is the impending regulatory shift in the world’s largest battery market. Starting September 1, 2026, China will implement a 2% consumption tax on lithium-ion batteries. This policy is designed to cool over-investment in the domestic manufacturing sector and encourage higher-value technology exports.
The impact of this tax is twofold:
- Margin Compression: Battery manufacturers may attempt to pass these costs upstream to mineral suppliers, placing further downward pressure on lithium carbonate prices as they approach the 2026 implementation date.
- Market Bifurcation: The tax may accelerate the development of non-Chinese supply chains (the “ex-China” market), as international buyers seek to avoid the cascading costs associated with Chinese-refined chemicals and assembled cells.
This policy change is expected to create a period of heightened volatility in the months leading up to September 2026, as manufacturers front-load orders to beat the tax deadline, followed by a potential “demand vacuum” in the final quarter of that year.
Demand Decoupling: ESS vs. EV Volatility
While the EV sector remains the primary driver of lithium consumption, it is no longer the sole determinant of market health. Stationary Energy Storage Systems (BESS) are showing a distinct decoupling from the consumer-led EV market. Grid-scale storage projects are driven by long-term infrastructure mandates and the global transition to renewable energy, making them less sensitive to high-interest rates and shifting consumer sentiment that has plagued EV adoption rates.

In 2026, ESS demand is projected to account for a significantly larger portion of the total lithium market share compared to 2023 levels. This “decoupling” provides a vital safety net for prices. Even if EV sales growth remains sluggish, the build-out of renewable energy grids requires massive quantities of lithium-iron-phosphate (LFP) batteries, which favor the carbonate products currently facing the most pricing pressure.
Lithium Price Forecast 2026: Base, Bull, and Bear Cases
Given the current data, the consensus among major financial institutions and industry analysts suggests a price band of $18,000 to $25,000 per tonne for 2026. However, the path to these levels is fraught with geopolitical and operational risks.
| Scenario | 2026 Price Target (LCE) | Primary Drivers |
|---|---|---|
| Bear Case | $13,500 – $15,500 | Sustained oversupply from China/Africa; stagnant EV growth; tax-induced demand slump. |
| Base Case | $18,000 – $22,000 | Balanced market; ESS demand offsets EV volatility; marginal production stays online. |
| Bull Case | $25,000 – $32,000 | Project delays in Argentina; aggressive US/EU storage mandates; supply chain hoarding. |
The “base case” assumes that the $18,000 floor holds as producers manage output to avoid selling at a loss. However, if the 2027 glut fears materialize early, the market could see a temporary dip into the mid-teens as traders liquidate positions.
Operational Intelligence and Market Monitoring
For mining professionals and investors, navigating this environment requires real-time data integration. Control rooms at major extraction sites are increasingly focused on cost-curve optimization rather than pure volume. As the industry matures, the ability to pivot between different grades and chemistries: such as shifting from battery-grade to technical-grade when spreads narrow: will be a key competitive advantage.

At Skillings, we continue to track these developments through our comprehensive mining news updates, providing the analysis necessary to stay ahead of the commodity cycle. The 2026 lithium market will likely be defined by “selective resilience”: where projects with low-cost bases and secured offtake agreements thrive, while higher-cost lepidolite and junior explorers face a challenging capital environment.
Conclusion: The Road to 2027
The current five-month low in lithium prices is a reminder of the sector’s inherent volatility, but it should not be mistaken for a permanent decline. The testing of the $18,000 floor is a healthy, albeit painful, recalibration of a market that was previously overheated.

As we move toward 2026, the focus will shift from “how much lithium is being mined” to “how much lithium can be refined and utilized efficiently” under new tax regimes and storage requirements. For those following battery minerals, the next 18 months will offer a critical window for positioning ahead of the structural deficits projected for the end of the decade.