SANTIAGO, Chile : Codelco, Chile’s state-owned mining giant, has officially revised the development timeline for its flagship Maricunga lithium project, pushing the expected start of production to 2034. The announcement, confirmed by Codelco Chairman Bernardo Fontaine during a Chilean Senate hearing, represents a four-year delay from the government’s previous 2030 target.
Despite the extended timeline, the project’s strategic alliance remains intact. Rio Tinto, the world’s second-largest miner, continues as Codelco’s primary partner, holding an approximately 49.99% stake in the joint venture. The partnership is a cornerstone of Chile's National Lithium Strategy, aimed at boosting the country’s output of battery-grade metals through state-led public-private partnerships.
Regulatory and Logistical Complexity Behind the Delay
The shift to a 2034 start-up is attributed to a combination of protracted regulatory approvals and logistical challenges inherent in the high-altitude Salar de Maricunga. Specifically, the Ministry of Mining is currently revising the Special Operating Contract (CEOL) to address observations made by the Comptroller General, a necessary step for finalizing the joint venture’s legal framework.
International regulatory hurdles have also contributed to the revised schedule. While approvals have been secured from authorities in Brazil, South Korea, and Poland, sign-offs from Chile and China remain pending. Codelco executives noted that the exploration and study phase must be exhaustive to ensure the technical viability of the brine extraction process in a region known for its complex hydrogeology.
The delay comes at a critical time for the global lithium market, where producers are navigating a lithium price forecast 2026 characterized by high volatility and a gradual recovery from 2024 lows.

Rio Tinto’s Strategic Commitment
Rio Tinto’s involvement in Maricunga is part of its broader push into the lithium sector, which recently included the acquisition of Arcadium Lithium. Under the binding agreements for the Maricunga JV, Rio Tinto is expected to provide US$350 million for studies leading up to a final investment decision (FID).
If the partners proceed after the study phase, Rio Tinto has committed an additional US$500 million toward construction costs. This staged funding model ensures that capital is deployed only as the project de-risks, particularly given the decade-long lead time now projected for first production.
Analysts suggest that Rio Tinto’s persistence in the project, despite the 2034 delay, underscores its long-term view of lithium demand driven by the global energy transition. However, project economics remain sensitive to market conditions; some scenario analyses suggest that sustained lithium carbonate prices below US$10,000 per tonne could impact the incentive for the final US$500 million construction tranche.
Lithium Price Forecast 2026: Market Implications
The removal of Maricunga’s anticipated supply from the late 2020s and early 2030s balances is viewed as supportive of medium-term prices. For 2026, the market is balancing significant new supply from Australia and Africa against a steady rise in electric vehicle (EV) adoption.
Investment banks have divergent views on the lithium price forecast 2026, with estimates ranging from bearish projections of persistent oversupply to bullish cases centered on a structural deficit by the late 2020s.
Analyst Price Forecasts for Lithium Carbonate (2026)
| Institution | 2026 Forecast (US$/t LCE) | Sentiment / Case |
|---|---|---|
| Goldman Sachs | US$8,900 – $13,250 | Bearish / Oversupply persistent |
| Skillings Base Case | US$12,000 – $14,000 | Neutral / Balanced market |
| Bernstein | US$17,000 | Bullish / Recovery phase |
| S&P Global | US$12,000 – $17,000 | Moderate / Rebound from 2025 |
| Fastmarkets | ~US$23,800 | Highly Bullish / Supply tightness |
Note: Data reflects aggregated analyst ranges for battery-grade lithium carbonate equivalent (LCE) for the 2026 calendar year.

Impact on Chile’s National Lithium Strategy
Chile remains the world's second-largest lithium producer, but it has faced increasing competition from spodumene producers in Australia and rising production in China. The National Lithium Strategy, introduced by President Gabriel Boric, seeks to reclaim market share by developing the Maricunga and Atacama salars through state-controlled entities.
The delay of Maricunga means that Chile’s near-term growth will rely almost entirely on the expansion of existing operations by SQM and Albemarle in the Salar de Atacama. Codelco recently finalized a landmark agreement with SQM to extend its operations in Atacama through 2060, providing a more immediate boost to state coffers than the long-dated Maricunga development.
For investors, the 2034 timeline for Maricunga shifts the focus toward junior miners and alternative lithium sources that can reach the market sooner. Developments in autonomous drilling and AI-ready processing may eventually help speed up these long lead-time projects, but for now, regulatory "bottlenecks" remain the primary obstacle in Chile.
Operational and Logistical Hurdles
Maricunga is significantly smaller than the Salar de Atacama but contains higher-grade lithium than many other global salars. However, its geography presents unique challenges. The salar is located at over 3,700 meters above sea level, requiring specialized equipment and infrastructure to handle extreme temperatures and thin air.
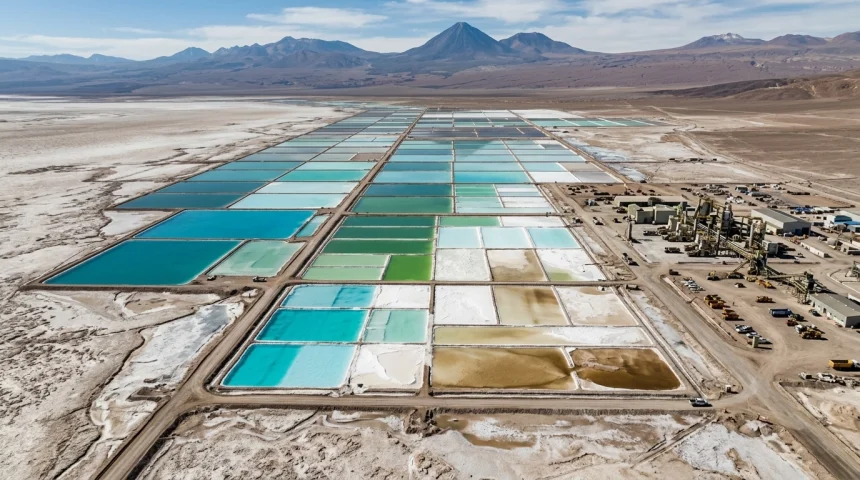
Logistically, the project requires the construction of extensive evaporation ponds and processing facilities in a remote region with limited existing power and water infrastructure. Codelco and Rio Tinto are exploring Direct Lithium Extraction (DLE) technologies as a potential method to improve yields and reduce the project’s environmental footprint, though traditional evaporation remains the base-case technology for the current feasibility studies.

Strategic Outlook: 2026 and Beyond
As the industry looks toward the next decade, the Maricunga delay serves as a reminder of the "permitting trap" facing many critical mineral projects worldwide. While the Skillings Mining Intelligence reports highlight a growing pipeline of lithium projects, the conversion rate from exploration to production remains low.
For operators and investors, the key takeaways from the Codelco-Rio Tinto announcement are:
- Medium-Term Supply Tightness: The removal of Maricunga’s 20,000–30,000 tonnes per annum (tpa) target from the 2030 supply stack may tighten the market earlier than anticipated.
- State-Private Collaboration Risks: The delay highlights the administrative complexities of the Chilean state-led model, which can slow project execution compared to purely private ventures.
- Rio Tinto's Patience: Rio Tinto's continued presence suggests it views lithium as a multi-decade play, less sensitive to the lithium price forecast 2026 and more focused on the 2035+ demand curve.
Codelco’s focus for the remainder of 2026 will be finalizing the JV structure with Rio Tinto and completing the revised CEOL process. Until these legal frameworks are solidified, the Maricunga project remains a "paper asset" in a market that is increasingly hungry for real-world production.
Social Media Snippet (LinkedIn/X):
Major shift in the #lithium landscape: Codelco has pushed the Maricunga project start date to 2034, a four-year delay. With Rio Tinto remaining a key partner, what does this mean for the global supply balance and the #LithiumPriceForecast for 2026? We break down the regulatory hurdles, analyst price targets, and the impact on Chile’s National Lithium Strategy.
Read the full analysis by Penny Langford: [Link]