Copper consolidation is moving beyond headline mergers. The emerging strategy combines large-scale corporate integration, project-level commitments, minority partnerships and district-scale exploration. For operators and investors, the question is no longer simply who is buying whom. It is whether consolidation can deliver additional copper supply at an acceptable cost, within a workable permitting framework and without overpaying for long-dated growth.
The proposed Anglo American-Teck combination remains the clearest example. First Quantum Minerals is advancing Taca Taca in Argentina, but still faces a financing and permitting path before construction. Glencore’s Democratic Republic of Congo portfolio is producing more copper while adapting to cobalt export restrictions. In Australia, Sibanye-Stillwater has approved the restart of the Mt Lyell copper-gold project. Meanwhile, Aya Gold & Silver is expanding its Moroccan exploration footprint around a producing silver business and a polymetallic development pipeline.
Together, these developments show how copper value is being distributed across different stages of the mining cycle.
Copper consolidation is becoming a supply strategy
Anglo American and Teck are preparing to combine into Anglo Teck, a top-five global copper producer with expected annual copper output of approximately 1.35 million tonnes and more than 70% exposure to copper.
The companies have also moved from transaction planning toward integration design. Their future executive leadership team has been announced, subject to completion of the merger and final regulatory approvals. The companies continue to guide toward completion within the previously stated window, although reviews in jurisdictions including China, the European Union and South Korea remain important conditions.
The financial case rests on two separate layers of value creation:
- Approximately US$800 million in annual pre-tax corporate synergies by the fourth year after completion.
- Approximately US$1.4 billion in average annual EBITDA uplift, on a 100% basis from 2030 to 2049, through operational integration and optimisation of the adjacent Collahuasi and Quebrada Blanca assets in Chile.
The second figure is particularly important because it is tied to physical assets rather than only corporate overhead. Shared infrastructure, mine planning, processing coordination and improved use of existing facilities could create value across the Chilean district.

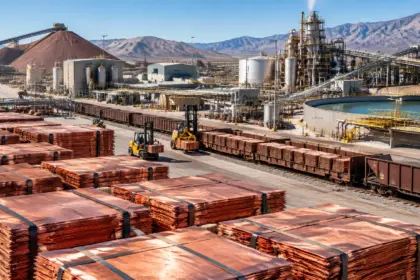
Large-scale copper infrastructure illustrates the operational logic behind district consolidation.
However, the valuation depends on execution. Quebrada Blanca has already experienced cost, schedule and ramp-up challenges. Any integration plan must therefore demonstrate that the projected synergies are achievable without adding excessive capital, disrupting production or creating new permitting obligations.
For shareholders, the relevant test is not the headline production ranking. It is the difference between stated synergies and delivered free cash flow.
Comparison: five consolidation and supply signals
The projects and portfolios now shaping the copper narrative sit at very different stages. Comparing them directly helps separate committed supply from optionality.
| Asset or transaction | Primary metals | Current position | Disclosed scale or value marker | Main valuation question |
|---|---|---|---|---|
| Anglo American–Teck / Anglo Teck | Copper, iron ore, zinc and other metals | Merger integration and regulatory review | ~1.35 Mt annual copper output; US$800M corporate synergies | Can integration convert scale into sustainable cash flow? |
| Taca Taca, Argentina | Copper, gold and molybdenum | Feasibility, permitting and financing | ~US$5.25B estimated development capital; 35-year mine life | Can First Quantum fund and de-risk a major greenfield project? |
| Glencore DRC assets | Copper and cobalt | Producing; portfolio and quota strategy under review | 397 kt group copper production in H1; 2026 guidance of 810–870 kt | How should copper growth be valued amid cobalt and policy constraints? |
| Mt Lyell, Tasmania | Copper and gold | Board-approved brownfield restart | ~A$490M capital; first production targeted for 2029 | Can existing infrastructure reduce restart and execution risk? |
| Aya Morocco portfolio | Silver, copper, gold, lead, zinc and critical minerals | Producing, development and exploration stages | Portfolio expanded to more than 991 km² | Can land consolidation generate discoveries without excessive exploration spend? |
Sources: company disclosures from Anglo American, First Quantum Minerals, Glencore, Sibanye-Stillwater and Aya Gold & Silver.
Taca Taca: commitment without a final construction decision
First Quantum continues to describe Taca Taca as its next major copper growth project. Located in Salta province in northwestern Argentina, the project is designed as a large conventional open-pit operation with copper, gold and molybdenum production.
The latest project materials cite 441 million tonnes of measured copper mineral resources and 1.637 billion tonnes of indicated mineral resources containing copper, gold and molybdenum. Updated studies have contemplated initial processing of 40 million tonnes per year, with a potential expansion to 60 million tonnes per year.
The estimated capital requirement of approximately US$5.25 billion makes Taca Taca strategically significant but financially demanding. First Quantum has been advancing its environmental and social baseline work, engaging with local communities and authorities, and working with the International Finance Corp. on sustainable development.
The company is also reported to be seeking a minority partner. That would allow First Quantum to share capital requirements and country risk while retaining exposure to one of the world’s largest undeveloped copper projects.
The distinction between commitment and construction is important. Taca Taca remains a long-term supply option until permitting, financing and a final investment decision are completed. Its valuation should therefore reflect both its resource scale and the substantial capital still required before production.
Glencore’s DRC evaluation: copper growth versus policy exposure
Glencore’s Democratic Republic of Congo operations demonstrate a different form of consolidation risk. The company already controls producing copper-cobalt assets, including Kamoto Copper Company and Mutanda, but its operating strategy is being reshaped by the DRC’s cobalt export quota regime.
Glencore reported own-sourced copper production of 397,000 tonnes in the first half, up 15% from the prior-year period. Cobalt production fell 46% to 10,200 tonnes, with the company attributing the decline largely to quota-related decisions and a greater focus on copper production.
The DRC assets are therefore being evaluated through operating priority, inventory management and potential ownership structures rather than through a straightforward acquisition announcement. Cobalt contained in mixed ore is increasingly being held in solution or stored in-country, while copper production remains central to the operating plan.
Glencore has also disclosed a nonbinding arrangement involving a proposed strategic stake for the US-backed Orion Critical Mineral Consortium. Such a structure could bring additional capital and Western supply-chain alignment while leaving Glencore as operator.
For valuation purposes, the DRC portfolio offers substantial copper exposure, but its risk profile cannot be assessed through copper volumes alone. Investors must also consider export rules, government relations, cobalt inventory, ownership terms, infrastructure and the potential for policy changes to alter the value of co-produced metals.

Copper and cobalt operations in the DRC are being managed around changing export conditions.
Mt Lyell: brownfield value with a long execution runway
Sibanye-Stillwater’s board approval to proceed with the Mt Lyell copper-gold restart highlights the appeal of brownfield development during a period of high copper prices.
The historic Tasmanian mine is expected to enter project execution in 2027, with first production targeted for early 2029. The project carries approximately A$490 million in capital requirements and is expected to produce more than 26,000 tonnes of copper and more than 16,000 ounces of gold annually at steady state.
The project’s attraction is its existing infrastructure, underground development, established logistics and access to renewable hydropower. Sibanye’s project materials cite a 23-year life of mine, a post-tax net present value of approximately US$550 million and a post-tax internal rate of return of about 20% under the current project basis.
Still, board approval is not the same as production certainty. Mt Lyell has a long history, complex underground workings and environmental obligations associated with a legacy operation. Mine-water treatment, tailings management, rehabilitation and workforce mobilisation will remain central to the restart plan.
The project illustrates an important valuation principle: brownfield assets can reduce upfront complexity, but they do not eliminate technical, environmental or schedule risk.

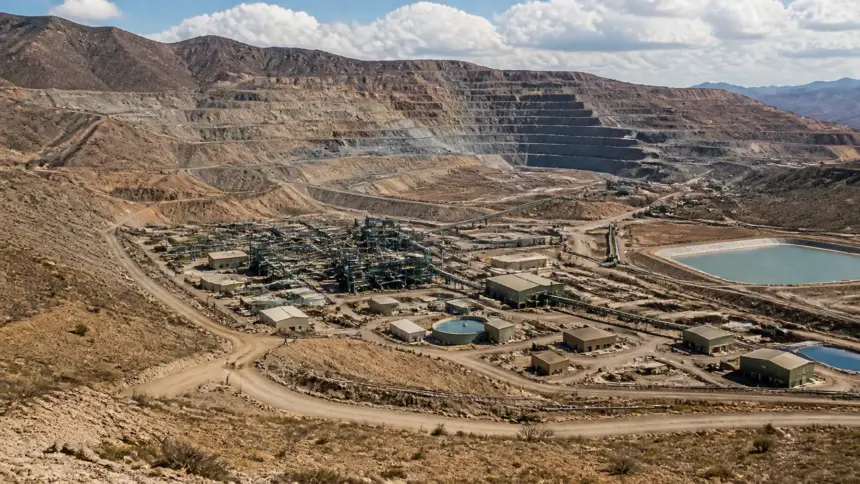
Mt Lyell’s restart case is based on existing infrastructure and a staged execution plan.
Aya’s Morocco portfolio: consolidation before discovery
Aya Gold & Silver is pursuing a different model. Its Moroccan strategy combines an operating silver mine, a major polymetallic development project and a growing exploration land package.
The company’s acquisition of three mining licences and 18 exploration permits added approximately 259 square kilometres across the Zagora, Agadir-Melloul and Goulmim projects. Aya says its total Moroccan land package has now expanded from approximately 732 square kilometres to more than 991 square kilometres.
The acquisition broadens exposure beyond silver. Zagora is prospective for nickel, cobalt, lead, zinc, silver and gold. Agadir-Melloul includes copper-silver-gold and rare earth potential. Goulmim is prospective for lead, silver, copper and gold.
Aya plans an 18- to 24-month greenfield programme involving stream-sediment geochemistry, hyperspectral analysis, mapping and prospecting. The purpose is to rank targets before committing to more expensive geophysics and drilling.
This approach limits the immediate capital burden, but it also means the acquired ground should not be valued as an established copper resource. The near-term value comes from land position, geological potential and strategic adjacency. Discovery, permitting and development remain uncertain.

Morocco’s expanded exploration portfolio adds copper, silver and critical-mineral optionality.
What consolidation means for valuation
The current pipeline suggests three broad valuation categories:
| Scenario | Value creation mechanism | Principal risk |
|---|---|---|
| Integration-led | Synergies, shared infrastructure and improved operating performance | Synergies may require more capital or take longer to realise |
| Project-led | New copper supply from Taca Taca or Mt Lyell | Permitting, financing, construction and ramp-up delays |
| Exploration-led | Larger land positions and district-scale discoveries | Early-stage assets may not convert into economic resources |
The market may reward consolidation when it improves cost position, mine life or infrastructure utilisation. It may discount deals when the buyer inherits difficult assets, takes on excessive capital commitments or relies on optimistic commodity assumptions.
Operators should track:
- Copper production added versus production merely consolidated.
- Capital intensity per incremental tonne.
- Treatment charges and concentrate availability.
- Permitting milestones and community agreements.
- Ownership changes in high-risk jurisdictions.
- The timing and credibility of synergy delivery.
- Whether exploration spending is generating defined resources.
The key conclusion is that copper consolidation is not a single trade. Anglo Teck represents corporate and district integration. Taca Taca represents large-scale greenfield optionality. Glencore’s DRC position shows how geopolitical and policy risk can reshape existing production. Mt Lyell demonstrates the value and limitations of brownfield restarts, while Aya’s Moroccan portfolio shows how exploration consolidation can build future supply before a discovery is confirmed.
For decision-makers, the strongest assets will be those that convert ownership, infrastructure and geological potential into permitted tonnes at competitive costs. Until then, deal size and resource scale remain useful indicators; but not substitutes for deliverable supply.
Sources
- Anglo American and Teck announce future Anglo Teck Executive Leadership Team
- First Quantum Minerals: Taca Taca project
- First Quantum Taca Taca technical report
- Glencore Half-Year Production Report
- Sibanye-Stillwater: Mt Lyell project
- Aya Gold & Silver acquires strategic exploration portfolio in Morocco
- Skillings copper market analysis
- Skillings copper price outlook