The global copper market is entering a pivotal transition phase where traditional industrial demand is being outpaced by the dual pressures of the energy transition and the rapid expansion of artificial intelligence infrastructure. For those tracking the copper price forecast 2026, the narrative has shifted from a simple cyclical recovery to a structural realignment of the entire supply-demand balance.
While 2024 and 2025 were characterized by volatility and macroeconomic uncertainty, 2026 is emerging as the year when long-warned supply deficits may finally manifest in sustained price appreciation. BMI (a Fitch Solutions company) recently hiked its forecast for the red metal, projecting a 6.7% increase as the market tightens. This sentiment is echoed across major financial institutions, with several banks revising their 2026 targets upward to reflect a world that is fundamentally short of copper.
The AI impulse: Beyond the cooling fans
While much of the copper market's long-term bullishness is tied to electric vehicles (EVs) and renewable energy grids, the sudden surge in AI-driven data center construction has provided a new, high-intensity demand pillar. Data centers are significantly more copper-intensive than traditional commercial buildings, requiring vast amounts of the metal for power distribution, transformers, and cooling systems.
Industry analysts note that a typical large-scale data center can require between 25 and 40 tonnes of copper per megawatt of power capacity. As hyperscalers like Microsoft, Google, and Amazon accelerate their AI hardware deployments, the demand for high-voltage cabling and efficient heat exchange systems is placing unprecedented pressure on refined copper stocks. Goldman Sachs has highlighted this trend, noting that grid and power infrastructure investments: backed by AI and defense sectors: will provide a solid floor for prices even if broader industrial activity remains tepid.

The supply-side crunch: A legacy of underinvestment
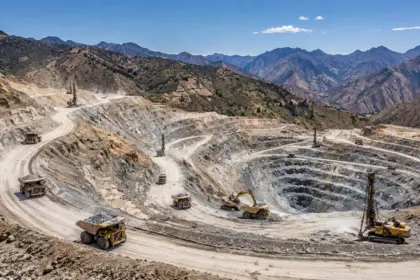
On the supply side, the 2026 outlook is increasingly defined by what is missing from the market rather than what is being added. The industry continues to grapple with the fallout from major project disruptions, most notably the closure of the Cobre Panama mine. While the Panamanian government is considering a state-owned model to reopen the facility, the timeline for significant production remains murky.
Furthermore, the "easy" ore has largely been mined. Existing operations in Chile and Peru: the world's primary copper hubs: are facing declining ore grades, which require more energy and water to process the same amount of finished metal. According to the IEA Mineral Risk Report 2026, midstream bottlenecks and the slow pace of permitting for new "greenfield" projects mean that even as prices rise, the physical supply response will likely lag by several years.
Exploration successes, such as Vizsla Copper’s high-grade porphyry discovery at the Thira project, provide some long-term optimism, but they are unlikely to bridge the immediate gap expected by 2026.
Institutional outlooks: A comparison of 2026 price targets
The divergence in institutional forecasts for 2026 reflects differing views on how quickly the supply deficit will bite. While some, like Goldman Sachs, see a market in mild surplus that caps prices near $11,000 per tonne, others like Citi and S&P Global see a much tighter path forward.
Below is a comparison of institutional price targets for copper in 2026:
| Institution | 2026 Price Target (LME Cash / Avg) | Key Driver Cited |
|---|---|---|
| BMI (Fitch) | +6.7% vs 2025 levels | Supply deficit & AI infrastructure |
| S&P Global | $12,100 / tonne | Concentrate shortages & grid demand |
| Goldman Sachs | $10,710 – $11,395 / tonne | Supported by AI; capped by mild surplus |
| JP Morgan | $11,000 / tonne | 160,000 tonne global deficit |
| Citi (Base Case) | $12,000 / tonne | Structural demand growth |
| Citi (Bull Case) | $15,000 / tonne | Supply restrictions & critical low inventory |
| ICSG (Nasdaq) | $10,635 / tonne | Record highs possible as deficits emerge |
Most institutions now place the "fair value" for copper in 2026 between $10,500 and $12,500 per tonne. However, the recurring theme in bull-case scenarios is the risk of a "melt-up" to $15,000 if the 330,000-tonne global supply deficit projected by some analysts becomes a reality.

Geopolitical risks and resource nationalism
The path to these price targets is not without its hurdles. Geopolitics will play a massive role in copper’s 2026 performance. Governments in resource-rich nations are increasingly looking to capture a larger share of mining profits through royalties and taxes: a trend known as resource nationalism.
In addition to domestic policy shifts, international trade tensions are a significant variable. Anticipated U.S. tariffs on imported copper could disrupt global trade flows, potentially leading to localized shortages and price spikes in the North American market. As noted in recent reports on the critical minerals supply chain, Western projects are accelerating, but they remain vulnerable to the same permitting delays and high capital costs that have hampered the industry for the last decade.

The role of scrap and substitution
As prices approach the $12,000 per tonne mark, the market will naturally look for alternatives. In some applications, aluminum can be used as a substitute for copper, though it often comes with a performance penalty in terms of conductivity and weight.
Scrap copper will also play an essential role in balancing the market. High prices incentivize the collection and recycling of old cabling and industrial waste. However, secondary supply is rarely enough to offset a structural shortfall in primary mine production, especially when the demand is coming from high-spec applications like AI data centers where material purity is paramount.
Outlook for 2026: A market of two halves?
Many analysts, including those at Goldman Sachs, suggest that 2026 could be a year of two halves. The first half may see prices driven by the "pre-loading" of inventories as companies rush to secure supply ahead of projected deficits. The second half could see a normalization if supply-side issues in Latin America are partially resolved or if global interest rates remain high enough to dampen overall economic growth.
Nonetheless, the consensus remains that the floor for copper has moved permanently higher. The days of $6,000 or $7,000 copper are increasingly viewed as a relic of the pre-energy transition era.

Conclusion
The copper price forecast 2026 points toward a market characterized by structural scarcity. Whether the average price settles at BMI’s projected 6.7% increase or reaches for Citi’s bullish $15,000 target will depend on three factors: the speed of the AI infrastructure rollout, the ability of major mines to maintain output amid declining grades, and the geopolitical stability of the "Copper Belt."
For investors and industry operators, 2026 represents a critical window. The convergence of digital and physical infrastructure needs is placing a burden on the copper supply chain that it is currently ill-equipped to handle, making the red metal one of the most strategic commodities of the decade.
LinkedIn/X Snippet:
Copper is entering a structural realignment. With BMI hiking its 2026 forecast by 6.7% and institutions like Citi eyeing bull cases of $15,000/t, the "red metal" is no longer just a cyclical play. AI data centers and supply-side deficits are the new drivers. #MiningNews #CopperPrice #AIInfrastructure #EnergyTransition