Jianxiawo’s suspension has turned permitting risk into a major variable for China’s lithium supply outlook.
Lithium price forecast 2026: CATL’s Jianxiawo mine in Jiangxi has returned to care and maintenance after regulators revoked its environmental approval, forcing Benchmark Mineral Intelligence to cut its forecast for the operation’s 2026 mined output to 32,000 tonnes of lithium carbonate equivalent (LCE) from 62,500 tonnes.
The downgrade removes 30,500 tonnes LCE from the previously expected supply contribution and highlights a broader risk for investors, battery manufacturers and mining companies: China’s lithium output may be constrained not by geology or processing capacity, but by the pace of environmental and operating approvals.
Jianxiawo has nameplate capacity of about 150,000 tonnes LCE per year, according to Mining.com. The revised forecast does not reflect a permanent loss of that capacity. It reflects the probability that the mine will produce little, if anything, for much of 2026 while CATL works through a renewed environmental review.
Jianxiawo’s permitting timeline has changed the supply equation
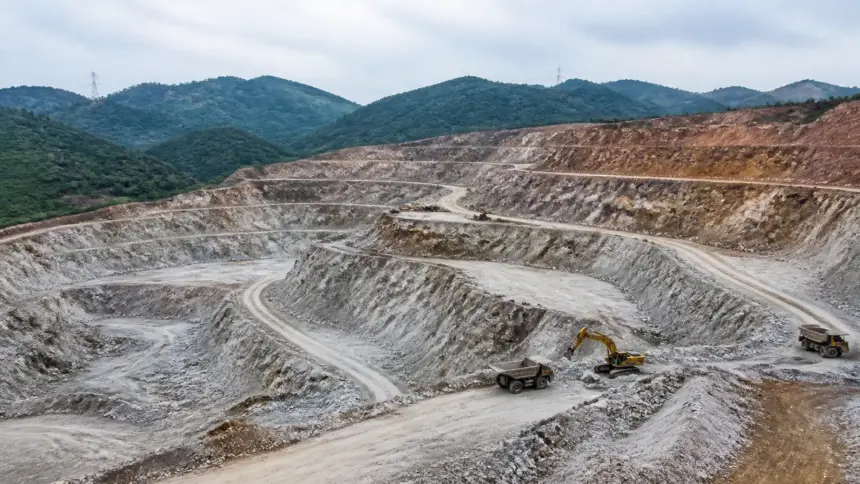
CATL suspended mining and refining at Jianxiawo in August 2025 after the mine’s operating licence expired. The shutdown came as Jiangxi authorities applied tighter scrutiny to lepidolite operations and to the classification of lithium-bearing clay deposits.
The company later secured a new safety production permit on June 29, 2026. That permit removed an important regulatory barrier and initially raised expectations that Jianxiawo could ramp up during the second half of the year.
Those expectations proved premature.
On Aug. 7, Mining Weekly reported, citing Chinese state media and the Yifeng County Ecology and Environment Bureau, that the mine remained closed pending environmental approval. Maintenance was taking place, but no ore transportation or crushing was underway.
The mine’s mineral designation had also changed from ceramic clay containing lithium to lithium ore. That change required CATL to prepare a new environmental impact assessment, or EIA. The draft EIA entered public consultation in late July, but final approval still requires additional procedural steps.
Benchmark said satellite imagery showed activity at Jianxiawo resuming briefly in June before stopping again during the first week of August. The evidence suggests that the safety permit allowed preparatory or limited work, but not a sustained commercial restart.
Benchmark’s latest assessment, summarized in its Jianxiawo analysis, is that the environmental approval process could extend into the fourth quarter or into 2027.
Capacity is large, but 2026 output will depend on timing
The distinction between capacity and realized production is central to the lithium price forecast for 2026.
| Jianxiawo supply measure | Tonnes LCE | What it indicates |
|---|---|---|
| Nameplate capacity | Approx. 150,000 per year | Long-term potential capacity cited by Mining.com |
| Earlier Benchmark 2026 forecast | 62,500 | Assumed an earlier and stronger restart |
| Revised Benchmark 2026 forecast | 32,000 | Reflects renewed environmental delays |
| Benchmark 2027 forecast | Approx. 99,000 | Assumes a more substantial recovery after approvals |
| Forecast reduction | 30,500 | Nearly 49% below the previous 2026 estimate |
The revised 32,000-tonne figure is less than half of the earlier forecast. It also represents only around 0.8% of global mined lithium supply if Benchmark’s previous estimate of 62,500 tonnes equating to about 1.5% is used as the reference point. That percentage is an analytical approximation rather than a separate Benchmark forecast.
For the market, however, the impact may be larger than the global percentage suggests. Jianxiawo is a major domestic source, and its production is linked to China’s conversion network. A shortfall in local feedstock can affect Chinese carbonate availability, procurement behavior and futures-market expectations even when global inventories remain adequate.

Processing and crushing activity at Jiangxi lithium sites will be closely watched for evidence of a sustained restart.
Three supply-deficit scenarios for lithium pricing
Jianxiawo alone does not determine lithium prices. The outcome will depend on how quickly other Chinese producers respond, the level of inventories held by converters and the pace of battery demand.
The following framework is designed to show how the mine’s status could affect the market rather than provide a fixed price target.
| Scenario | Jianxiawo assumption | Wider supply-demand balance | Likely pricing effect |
|---|---|---|---|
| Bear case: rapid normalization | EIA approval arrives quickly and production ramps toward the revised 2027 path | Other Jiangxi producers remain active; new Australian, African and South American supply grows on schedule | Prices remain capped by available inventory and recovering supply |
| Base case: delayed restart | Output is limited to about 32,000 tonnes LCE in 2026; fuller ramp occurs in 2027 | Supply growth falls short of combined EV and storage demand growth | A tighter balance supports firmer carbonate prices and greater volatility |
| Bull case: prolonged disruption | Environmental approval slips into 2027 and Jianxiawo contributes little or no additional 2026 supply | Other Jiangxi mines face delays, while competing projects underperform | A material deficit becomes possible, increasing competition for feedstock and lifting price risk |
The base case is increasingly important because the disruption is no longer simply a temporary licence expiry. It now includes a revoked environmental approval, a second review process and uncertainty over whether June activity represented a genuine restart.
The bull case would require additional disruptions elsewhere. Those could include further Jiangxi licence suspensions, delays at hard-rock mines outside China, weaker-than-expected output from Australia or restrictions affecting concentrate flows. A single mine would not necessarily create a global deficit, but several modest disruptions could remove the surplus that has weighed on prices.
Demand is broadening beyond electric vehicles
The demand side of the market also needs to be separated into its main components.
Electric vehicles remain the largest structural driver of lithium consumption. However, stationary battery energy storage is becoming a more important source of incremental demand as grids add solar and wind capacity, manage peak loads and seek flexibility.
Benchmark reported that global battery energy storage system cell and system shipments nearly doubled in the first half of 2026 compared with the same period a year earlier. That does not translate one-for-one into lithium demand because chemistry mix, battery duration and inventory timing vary. It does, however, show why demand cannot be assessed only through monthly passenger EV sales.
China’s domestic industrial chain also has several layers of demand: lithium carbonate procurement by cathode producers, battery-cell manufacturing, exports of cells and storage systems, and inventory held by converters. The market can therefore tighten in stages. Spot prices may rise before a visible shortage appears in finished batteries if buyers begin rebuilding raw-material inventories.
At the same time, high prices can slow demand growth. Battery makers may draw down inventory, delay purchases or shift chemistry where technically possible. The result is a market in which supply disruptions can lift prices sharply in the short term, while demand destruction limits the duration of the move.

Lithium carbonate availability and converter inventories will help determine whether the disruption reaches downstream buyers.
Risks extend beyond CATL
The Jianxiawo case is also a test of Jiangxi’s wider regulatory environment.
A province-wide enforcement campaign has already raised questions about the durability of production at other lepidolite mines. Producers that rely on older permits, different mineral classifications or environmental arrangements may face closer scrutiny. The risk is not necessarily that every operation will close. It is that operators may experience longer approval timelines, lower utilization rates or higher compliance costs.
For downstream companies, this increases the value of supply diversification. Alternative spodumene concentrate, brine feedstock and recycled material may become more attractive, although substitution is constrained by qualification requirements, logistics and conversion economics.
For mine developers outside China, the episode reinforces a broader point: a project’s competitive position depends on permitting certainty as much as on resource size and operating costs. Skillings’ coverage of the critical minerals supply chain examines this wider relationship between policy, processing and market access.
Indicators to watch through the next restart attempt
The most useful signals will be operational and administrative rather than speculative headlines.
- EIA milestones: Watch for formal acceptance of the environmental report, the end of public consultation and a final approval decision.
- Ore movement: Satellite imagery and local government notices showing sustained crushing, haulage and stockpile activity would be stronger evidence than isolated site work.
- Jiangxi-wide enforcement: New licence decisions affecting neighboring lepidolite mines could change the regional supply balance.
- Chinese carbonate inventories: Falling converter and producer inventories would indicate that the suspension is moving from sentiment into physical availability.
- Spot-futures structure: A sustained shift from contango toward backwardation would suggest tighter nearby supply, although futures can also react to speculative positioning.
- EV and storage procurement: Battery production, storage shipments and cathode-maker purchasing will determine whether lost mine output is absorbed or amplified.
The central conclusion for the lithium price forecast for 2026 is not that Jianxiawo’s full capacity has disappeared. It is that the market can no longer assume that capacity will be available when required.
Until environmental approval is restored and sustained ore movement is visible, the mine should be treated as a delayed supply source. That leaves the 2026 lithium balance more exposed to demand growth, inventory drawdowns and additional disruptions across Jiangxi and other producing regions.
Sources: Mining.com; Mining Weekly; Benchmark Mineral Intelligence.