The global nickel market is entering a period of forced rebalancing as Indonesia, the world’s dominant supplier, moves to tighten its grip on ore production through 2026. After two years of persistent oversupply that pressured prices and shuttered high-cost operations globally, the narrative is shifting from a structural surplus toward a managed deficit.
The primary catalyst for this transition is the Indonesian government’s revision of its Work Plan and Budget (RKAB) mining quotas. For 2026, authorities have signaled a significant reduction in approved nickel ore production, targeting approximately 260 million to 270 million wet tonnes. This represents a sharp contraction from the 379 million tonnes allocated for 2025, creating a potential feedstock gap that domestic smelters may struggle to fill through imports or stockpiles alone.
For operators and investors, this policy shift represents the most significant structural change in nickel dynamics since the emergence of the “Indonesia discount” in early 2023. As the market absorbs the reality of capped Indonesian growth, the investment edge is moving toward identifying how these constraints will affect the battery-grade intermediate segment versus traditional stainless steel inputs.
The RKAB Crunch: Indonesia’s Strategic Supply Cap
Indonesia’s Ministry of Energy and Mineral Resources (ESDM) has maintained a firm stance on the 2026 RKAB quotas, despite initial speculation that the government might relax limits to support its vast smelting infrastructure. The Indonesian Nickel Miners Association (FINI) has indicated that domestic smelters likely require between 340 million and 350 million tonnes of ore to run at optimal capacity in 2026. The projected 260-270 million tonne cap implies an ore shortfall of nearly 80 million tonnes.
This deficit is not merely a logistical hurdle; it is a policy-driven floor for the market. By restricting ore availability, Jakarta is effectively managing the global price environment while protecting its domestic mineral reserves. This “managed tightness” is a departure from the unrestricted expansion seen over the last decade, signaling that the era of cheap, infinite Indonesian supply may be reaching a plateau.
Analysts at Goldman Sachs and Macquarie have already adjusted their 2026 price forecasts upward in response. Goldman Sachs raised its 2026 average price expectation to $17,200/t, noting that the tightening ore market will force a drawdown of refined nickel inventories that have accumulated since 2024.

Supply Chain Bottlenecks: The Sulphur Constraint in HPAL
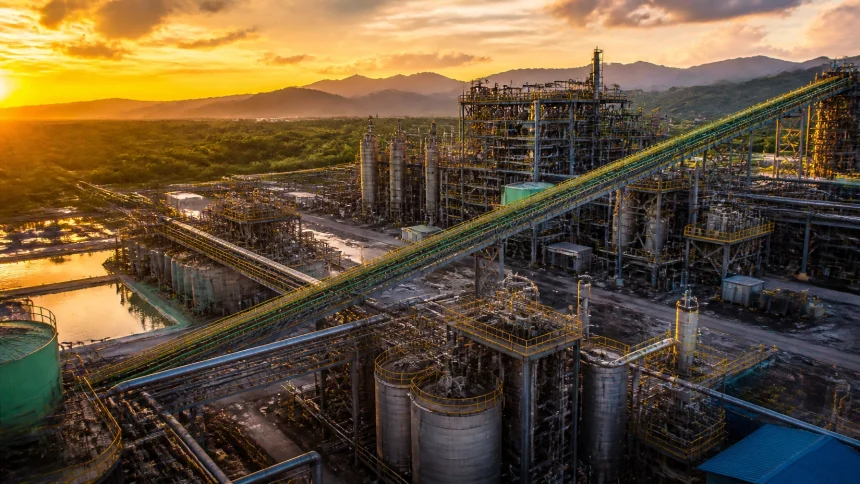
While ore quotas dominate the headlines, a secondary but equally critical bottleneck is emerging in the production of nickel intermediates, specifically for the electric vehicle (EV) battery supply chain. High Pressure Acid Leach (HPAL) plants, which process Indonesian laterite ores into Mixed Hydroxide Precipitate (MHP), are highly dependent on continuous supplies of elemental sulphur and sulphuric acid.
Indonesia’s rapid build-out of HPAL capacity has outpaced its domestic acid production infrastructure. Many operators now rely on imported sulphur to fuel on-site acid plants. Global supply chain disruptions or localized logistics failures in sulphur delivery could materially restrict HPAL utilization rates. Even if ore quotas were sufficient, a shortage of processing reagents like sulphur could prevent the market from realizing its full nameplate capacity for battery-grade nickel.
These operational constraints suggest that the “effective” supply of nickel in 2026 may be lower than many legacy forecasts suggest. If HPAL plants operate below 85% capacity due to reagent shortages or technical scaling issues, the transition to a market deficit could occur sooner and more sharply than anticipated.

Demand Dynamics: Stainless Resilience and EV Acceleration
On the demand side, nickel remains anchored by two distinct pillars: the legacy stainless steel sector and the accelerating energy transition.
Stainless steel, which accounts for nearly 65% of global nickel consumption, has shown surprising resilience despite broader macroeconomic headwinds. In China and Southeast Asia, production volumes have remained steady, providing a solid floor for Class II nickel (Nickel Pig Iron) demand. However, the true growth driver for the 2026 outlook remains the EV sector.
As battery chemistries continue to favor high-nickel formulations for long-range performance, the demand for MHP and nickel sulphate is projected to grow at double-digit rates through 2026. The International Nickel Study Group (INSG) has recently revised its 2026 global balance from a surplus of 283,000 tonnes to a deficit of 32,000 tonnes, specifically citing the intersection of constrained Indonesian ore and robust battery-sector demand.
Investors tracking these shifts often look toward royalty companies and established producers to hedge against the volatility inherent in junior exploration during such structural pivots.
Price Forecast 2026: The $17,000-$18,000 Baseline
The consensus among major financial institutions suggests that LME nickel prices will likely average between $17,000 and $18,000 per tonne in 2026.
- Base Case: Prices hold the $17,500/t level as Indonesia enforces its RKAB limits and global inventories begin to normalize.
- Bull Case: Strict enforcement of the 260 million tonne quota, combined with sulphur shortages at HPAL sites, could push prices toward $20,000/t as the market scrambles for high-purity units.
- Bear Case: A policy reversal in Jakarta that increases quotas back toward 350 million tonnes would likely see prices drift back toward the $15,000/t support level.
For decision-makers, maintaining a daily market analysis posture is essential, as the nickel market has proven highly sensitive to sudden regulatory shifts.

Market Snapshot: 2026 Nickel Fundamentals
| Indicator | 2025 (Estimated) | 2026 (Forecast) |
|---|---|---|
| Indonesian Ore Quota (RKAB) | 379 Mt | 260-270 Mt |
| Global Refined Supply | 3.55 Mt | 3.38 Mt |
| Global Nickel Demand | 3.44 Mt | 3.41 Mt |
| Market Balance | +110 kt (Surplus) | -32 kt (Deficit) |
| Average LME Price ($/t) | $16,200 | $17,500 |
Strategic Outlook
The 2026 nickel market will be defined by Indonesia’s transition from a volume-first strategy to a value-and-discipline strategy. While the rapid expansion of the previous years successfully captured market share, the current focus on quota management and environmental permitting (ESG) suggests a maturing industry. For the global mining sector, this shift provides a rare window of price support that may encourage investment in non-Indonesian jurisdictions that have struggled to compete during the recent surplus years.
As the industry prepares for this tightening, the ability to secure reliable feedstock and navigate the reagent-heavy processing requirements of HPAL will be the primary differentiator for successful operators in the mid-decade.