The planned consolidation would place SM Investments’ Atlas stake and other mining assets under Dominion Holdings.
SM Investments Corp. is preparing to move its mining assets into Dominion Holdings Inc., creating a dedicated mining platform that could become the Philippines’ largest listed gold and copper miner once the planned consolidation is completed.
The conglomerate intends to transfer its roughly 34% stake in Atlas Consolidated Mining and Development Corp. to Dominion by next year, SM Investments President and Chief Executive Frederic DyBuncio said during a media briefing on Wednesday.
The move would take mining out of SM Investments’ main portfolio while keeping the Sy family’s exposure to the sector within another listed company. Dominion is also expected to receive interests linked to the Tampakan copper-gold project in South Cotabato, a large undeveloped deposit that could transform the company’s scale if development proceeds.
“This intention for SMIC is to completely move out from the mining sector,” DyBuncio said, according to the Manila Bulletin.
The transaction is not yet a completed merger. The precise valuation, share-swap terms and legal structure for transferring SM Investments’ Atlas holding have not been disclosed. Tampakan’s potential inclusion in Dominion also remains subject to further corporate, regulatory and development decisions.
Dominion begins mining consolidation with Atlas stake
Dominion has already taken its first step into mining by acquiring a 20.43% interest in Atlas from Anglo Philippine Holdings Corp., a company associated with the Ramos family.
Under a deed of assignment signed on Aug. 7, Dominion acquired subscription rights covering 727.2 million Atlas shares for approximately ₱857 million in cash. The shares were partially paid, with Anglo having previously settled 25% of the subscription price.
Dominion will assume the remaining 75% obligation, estimated at ₱2.39 billion, when Atlas’ board calls the payment.
The transaction represents Dominion’s first mining investment. The company has said it intends to build a broader portfolio focused primarily on mining corporations, according to disclosures reported by the Philippine Daily Inquirer.
The acquisition also changes the balance of ownership around Atlas. SM Investments still owns approximately 34% of Atlas, while the Ramos family previously held a substantial position through several entities. Once SM Investments transfers its stake, Dominion would become the main listed vehicle for the Sy family’s Atlas exposure.
Atlas operates Carmen Copper Corp.’s mine and processing facilities in Toledo City, Cebu. The operation produces copper concentrate, with gold and silver as principal by-products.

Processing infrastructure supporting copper and precious-metals recovery.
Atlas returns to profit as metal prices rise
The restructuring comes as Atlas has benefited from stronger copper and gold prices, even while its Toledo operations have been working through a redevelopment program.
Atlas reported approximately ₱4.6 billion in net income in the first half of 2026, reversing a net loss of about ₱653 million in the same period a year earlier, according to reporting cited in the company’s interim disclosures.
Production, however, has remained under pressure. Carmen Copper produced approximately 37.2 million pounds of copper and 17,795 ounces of gold during the first half, with output affected by lower ore grades as mining progressed deeper into the pit.
The company’s redevelopment program at Toledo was reported to be on schedule for completion around the third quarter of 2026. That work is intended to support the mine’s longer-term operating performance, although production and earnings will remain exposed to grade, recovery rates, operating costs and metal prices.
Atlas’ recent operating performance illustrates the difference between asset ownership and production capacity. Higher commodity prices helped restore profitability, but the mine’s physical output has not yet fully recovered. For Dominion, the value of the consolidation will therefore depend not only on the size of its ownership position but also on the ability of its operating assets to deliver consistent volumes.
| Asset or transaction | Reported position | Relevance to Dominion |
|---|---|---|
| SM Investments’ Atlas stake | About 34% | Planned transfer to Dominion |
| Dominion’s Atlas acquisition | 20.43% | Acquired from Anglo Philippine Holdings |
| Atlas shares covered by assignment | 727.2 million | Subscription rights transferred |
| Cash consideration | About ₱857 million | Paid for the assignment |
| Remaining subscription obligation | About ₱2.39 billion | Payable when called by Atlas |
| Atlas H1 2026 net income | About ₱4.6 billion | Reversal of prior-year loss |
| Tampakan projected annual output | 375,000 tonnes of copper and 360,000 ounces of gold | Potential future scale |
Figures are based on company disclosures and Philippine business-media reports. Tampakan production estimates are prospective and subject to project development.
Tampakan is the larger strategic prize
The most significant part of the proposed structure is Tampakan, which is widely described as Southeast Asia’s largest undeveloped copper-gold project.
The project is located in South Cotabato on Mindanao and has been stalled for years by regulatory restrictions, local opposition and debate over open-pit mining. The Philippines lifted its national open-pit mining ban in 2021, although major permitting, environmental and community-consent issues remain relevant to the project’s timeline.
Tampakan’s owners have previously considered bringing in an outside strategic partner. More recent reporting indicates that the Sy and Consunji families are exploring a Filipino-backed development strategy, with Tampakan-related entities potentially merged into Dominion.
DyBuncio has said Tampakan could be infused into Dominion. If that occurs alongside the transfer of SM Investments’ Atlas stake, Dominion would combine a producing copper operation in Cebu with one of the country’s most important undeveloped copper-gold resources.
The project has previously been associated with an expected production start around 2028. Reported estimates point to average annual production of roughly 375,000 tonnes of copper and 360,000 ounces of gold in concentrate over a projected 17-year mine life.
Those figures are not yet operating results. They remain dependent on final project design, financing, permitting, construction, community agreements and successful commissioning.

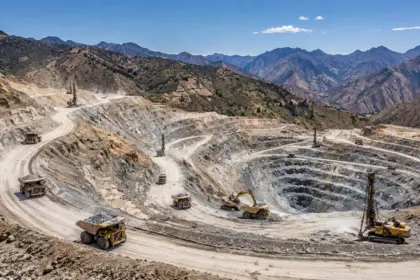
Mindanao’s mountainous terrain presents both resource potential and development challenges.
A new vehicle for the Sy and Consunji mining interests
Dominion’s repositioning follows changes in its ownership and board composition. The company was previously associated with BDO Unibank before being acquired by Monte Sur Equity Holdings, an entity linked to the Sy family.
Its board now includes senior figures from the Sy and Consunji groups, including Isidro Consunji as chair, Henry Sy Jr., DyBuncio and DMCI Mining President Tulsi Das C. Reyes.
That governance structure provides a framework for combining the families’ mining interests under one listed entity. It also separates those assets from SM Investments’ principal businesses, which include banking, property and retail.
DyBuncio said SM Investments plans to focus its portfolio investments on renewable energy and logistics after leaving mining. The conglomerate has six renewable-energy concessions under development and is also expanding logistics operations through 2GO Group, including cargo forwarding, project logistics and warehousing.
For Dominion, the approach could provide a clearer investment identity. A dedicated mining vehicle may make it easier to raise capital, attract technical partners or pursue additional acquisitions than would be possible inside a diversified conglomerate.
However, it also concentrates exposure to the cyclical and operational risks of mining. Dominion would be affected by copper and gold prices, mine redevelopment, permitting, environmental liabilities, local-community relations and the substantial capital requirements associated with Tampakan.
The key risks are still ahead
The proposed consolidation has generated significant interest in Dominion shares, which have risen sharply as investors anticipate the transfer of mining assets. The market response reflects expectations about future resource value rather than a completed production platform.
Several milestones will determine whether Dominion can become the country’s largest gold and copper miner by operating scale:
- Completion of the Atlas transfer. SM Investments must determine the transaction structure and obtain the necessary corporate and regulatory approvals.
- Funding of Atlas obligations. Dominion has assumed the remaining subscription liability connected with the 727.2 million Atlas shares.
- Completion of Toledo redevelopment. Carmen Copper must improve operating consistency while managing lower grades and deeper mining conditions.
- Formalization of Tampakan’s ownership structure. Any transfer of Tampakan-related entities would require definitive agreements and public disclosures.
- Permitting and social license. The project must address environmental, local-government and community concerns before construction can advance.
- Project financing and construction. Tampakan would require substantial capital and technical execution over several years before generating revenue.
The structure therefore creates a potentially important Philippine mining platform, but its eventual scale will depend on execution. Atlas provides an existing operating base, while Tampakan offers the prospect of much larger future production.

Control-room systems will be central to managing production, safety and project execution.
Implications for the Philippine mining sector
The planned consolidation comes as demand for copper and other critical minerals grows because of grid investment, electrification and energy-transition infrastructure. Copper remains central to power networks, renewable generation, electric vehicles and industrial equipment, while gold continues to provide a significant revenue stream for many polymetallic operations.
The Philippines has substantial mineral resources but has historically faced underinvestment, permitting delays and community opposition. A large, locally backed mining platform could encourage further exploration and demonstrate that major projects can be advanced through domestic capital and industrial partnerships.
That outcome is not assured. Tampakan’s history shows the difficulty of moving a large resource from discovery to production. The project has been discussed for decades, and its development schedule has shifted repeatedly.
For now, the confirmed transaction is Dominion’s acquisition of a 20.43% Atlas position and SM Investments’ plan to transfer its approximately 34% stake. The possible Tampakan contribution is the more consequential but less certain element.
If both moves proceed, Dominion would emerge as a consolidated Sy-Consunji mining vehicle with exposure to a producing copper-gold mine and one of the Philippines’ largest undeveloped mineral projects. For operators, investors and policymakers, the next focus will be the transaction documents, project approvals and evidence that the proposed platform can convert resource scale into reliable production.
For additional context, see Skillings’ coverage of mining finance and investment trends, copper-market disruptions, and critical-minerals supply chains.