Refining concentration in the critical minerals sector is creating dangerous chokepoints that could destabilize global clean energy ambitions, according to a new report from the International Energy Agency (IEA). As countries push to electrify transportation and expand renewable energy infrastructure, the bottleneck created by a few dominant refining nations—chiefly China—raises the risk of market disruptions, higher prices, and slower energy transitions.
The warning comes as the market for critical minerals—such as lithium, cobalt, copper, and rare earth elements—experiences historic demand growth, fueled by electric vehicle (EV) rollouts, solar panel manufacturing, and battery storage systems.
“Even in a well-supplied market, critical mineral supply chains can be highly vulnerable to supply shocks, bringing higher prices for consumers and reducing industrial competitiveness,” said IEA Executive Director Fatih Birol.
Global Refining Concentration Threatens Energy Security
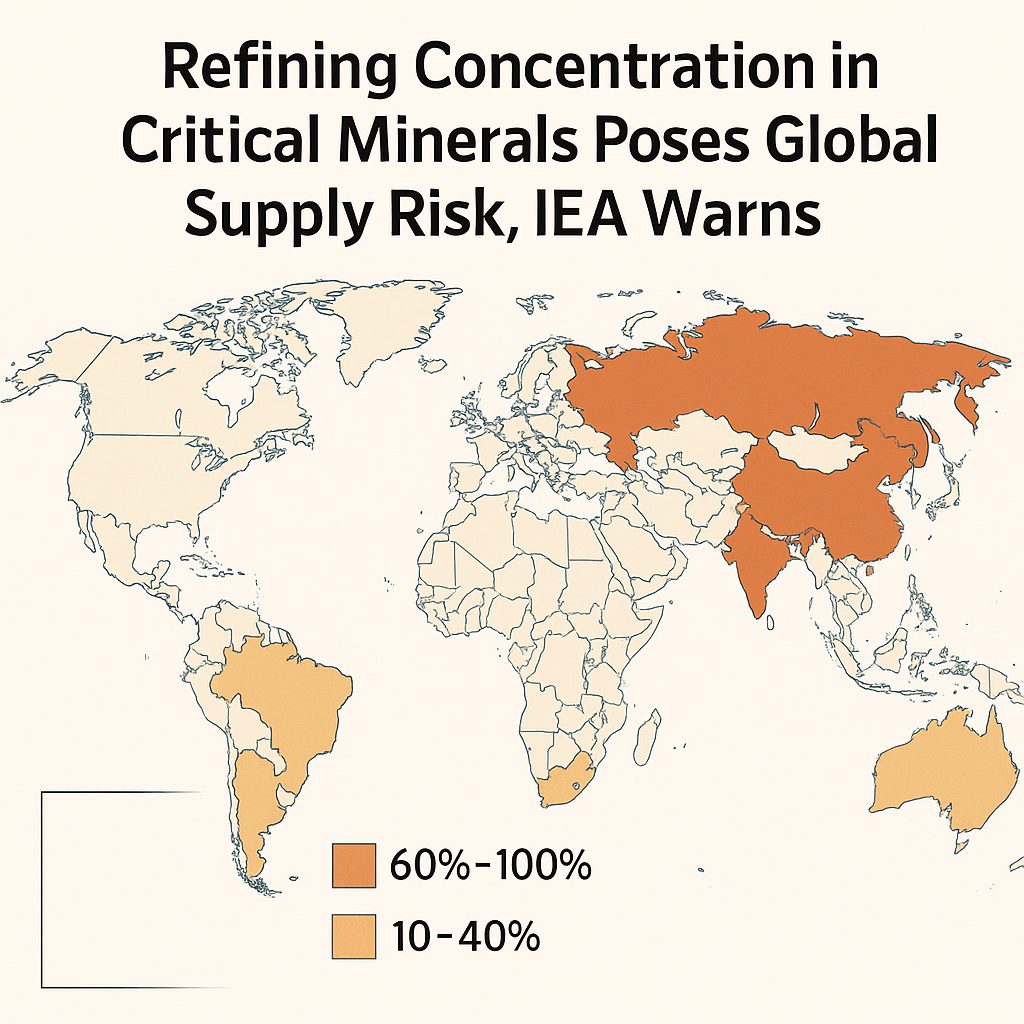
The IEA’s data paints a stark picture of refining concentration in global mineral processing. By 2035, the top three refining countries are expected to control approximately 82% of the refined material supply, a level of concentration that creates significant vulnerability in case of trade disputes, geopolitical tensions, or internal disruptions.
China, already the global leader in mineral refining, has rapidly expanded its processing capabilities and added more than two-thirds of global battery recycling capacity since 2020. This dominance has intensified global dependence on a single nation for downstream mineral processing.
The implications of this refining concentration go beyond price volatility. It exposes entire industries—including electric vehicles, energy storage, and clean tech manufacturing—to geopolitical leverage and logistical fragility.
Related News
- Rio Tinto Gallium Extraction Breakthrough Anchors North America Supply Chain
- China’s Latest Trade Weapon: The Seven Rare Earth Minerals Aimed at the U.S.
- Europe Rare Earth Production Falls Short as Demand Surges Toward 2030
- U.S.-China Trade War 2025 Heats Up as Beijing Targets Rare Earth Exports
Critical Minerals Supply at Risk Amid Demand Surge
While refining is the most concentrated point in the supply chain, upstream extraction also faces risk. The IEA report outlines significant challenges for the mining of key critical minerals.
For instance, copper, an essential component of power grids and EVs, could face a 30% supply shortfall by 2035, driven by falling ore grades, high production costs, and limited new project discoveries. Given that copper projects often take 10 to 15 years to develop, the outlook is increasingly constrained.
Meanwhile, lithium—crucial for EV batteries—is expected to remain in short supply during the 2030s despite more favorable investment conditions and permitting processes compared to copper. Demand for lithium continues to outpace production growth, with deficits expected unless significant new capacity is brought online.
China’s Refining Power Raises Global Alarm
China’s refining concentration is not only a market concern but a geopolitical flashpoint. The country refines the majority of the world’s rare earth elements and controls a substantial portion of cobalt, graphite, and lithium refining. This positions China as a gatekeeper to many of the materials needed for the energy transition.
Western governments have responded with policy tools to reduce dependency. The U.S. Inflation Reduction Act includes tax incentives for domestically sourced materials, while the EU’s Critical Raw Materials Act aims to diversify sourcing and increase strategic stockpiles.
Yet, progress has been slow. New refining facilities face long permitting timelines, environmental scrutiny, and capital intensity that discourage private-sector investment without government support.
Refining Diversification Lags Behind Mining
While mining for some minerals—such as lithium, graphite, and rare earths—is slowly diversifying, refining remains highly centralized. Australia, Canada, and select African nations are attempting to build processing capacity, but they remain far behind China in scale and integration.
The IEA recommends a global push toward refining diversification, improved recycling systems, and public-private investment in midstream infrastructure. Without it, the growing dependence on a few players may become an enduring risk for clean energy deployment.
Conclusion: Refining Concentration is the Achilles’ Heel of Clean Energy Supply Chains
As the world leans harder into electrification and decarbonization, refining concentration in critical minerals emerges as a central challenge. The IEA’s report underscores that diversifying both mining and refining is essential to building resilient, sustainable supply chains.
Without deliberate, coordinated action, today’s refining choke points could become tomorrow’s economic flashpoints—dragging on innovation and imperiling the very transition they were meant to enable.