2026 Lithium Power Map : Early Access Open ($59) | Get the latest sector data and secure your copy here: https://skillings.short.gy/LithiumPreSale
Today’s briefing follows the Skillings Mining Intelligence daily format: a concise roundup of the day’s most important mining developments, a market snapshot table, and clear takeaways for operators, investors, and policymakers.
The day’s key mining developments point to the same underlying theme: tighter control over critical mineral supply is colliding with surging demand from power, data center, and energy-transition markets. In Peru, uncertainty around a major copper project has sharpened questions about near-term supply. In North America, uranium and lithium stories continue to reinforce the strategic push for domestic and allied sources of critical materials.
Below is today’s briefing on the main stories shaping operator, investor, and policy attention across the sector.
1. Peru’s Copper Shock
Southern Copper’s Tía María permit has been revoked, threatening a $1.8 billion project and adding fresh uncertainty to the 2026 copper supply picture. The development matters well beyond Peru because Tía María has long been viewed as one of the more visible undeveloped copper projects in the Andean pipeline. Read the full analysis here: <BLOG_POST:699b1798-e168-4704-9e50-08d1fc3ffe12>
2. AI-Energy Nexus
Tech companies are moving deeper into mining districts as energy security and raw material access become strategic priorities. In Wyoming, uranium is increasingly being framed as a foundation for reliable power; in the Andes, copper remains central to grid expansion and electrification. Full story: <BLOG_POST:2cb47eb1-9aa8-4a92-b1b4-f50de7412fad>

3. U.S. Uranium Resurgence
Uranium Energy Corp has restarted production at Burke Hollow, while Eagle Nuclear has broken ground on the Aurora Roadmap in Oregon. Together, the developments underscore how U.S. uranium supply and associated nuclear infrastructure are being repositioned as part of the broader energy and industrial policy agenda. Full story: <BLOG_POST:8c9ae227-1929-46a6-811a-13a236b98d27>
4. Quebec’s Lithium Giant
Q2 Metals has unveiled a 295 million tonne resource at Cisco, strengthening Quebec’s standing in the North American lithium supply chain. The scale of the resource is likely to draw close attention from downstream battery and strategic materials watchers. Full story: <BLOG_POST:c1756058-c123-4d7e-bfdb-ecfc0c99c93f>
5. AI Discovery in the DRC
KoBold Metals, backed by Bill Gates and Jeff Bezos, has launched a $50 million AI-driven lithium search in the Democratic Republic of Congo. The move adds another example of machine learning being used not only to optimize operations, but to target frontier mineral discovery in jurisdictions with high geological potential and elevated execution risk.
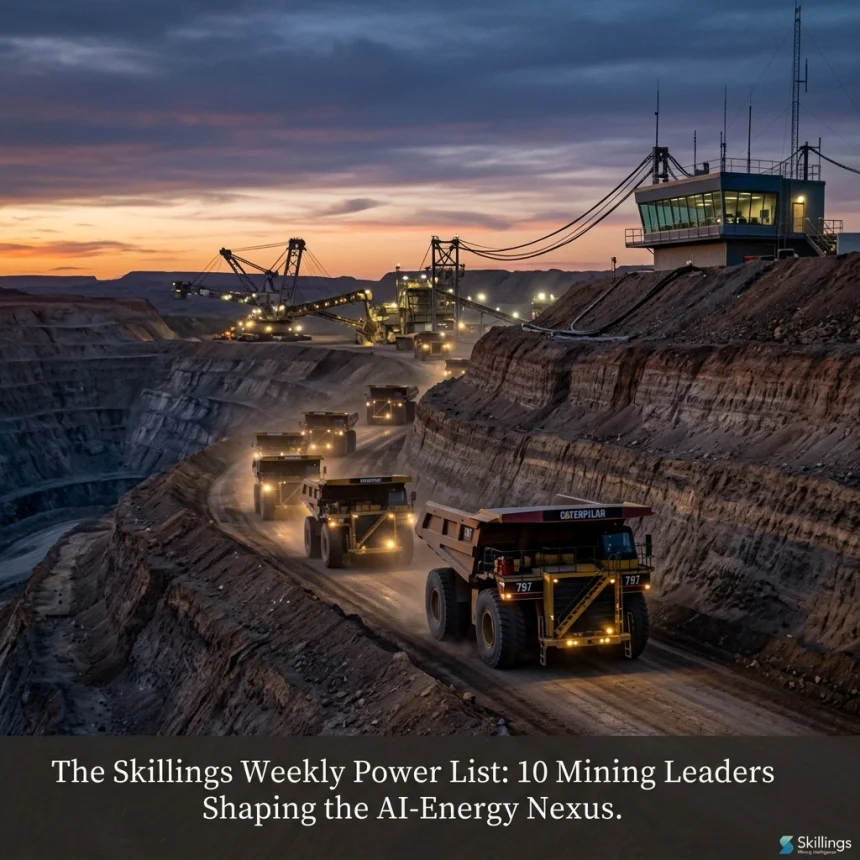
6. The Weekly Power List
A shorter view of leaders shaping the junction of mining and AI this week includes:
- Peter Grosskopf — for his continuing role in linking capital markets, uranium, and strategic resource themes
- Amir Adnani — as U.S. uranium production and policy momentum continue to build
- Richard Adkerson — for Freeport-McMoRan’s importance to copper supply in an increasingly power-hungry economy
- Kurt House — for pushing AI-led mineral discovery into large-scale field deployment
- Alicia Woods — as Q2 Metals gains visibility in the lithium growth story
Market Snapshot: Critical Minerals and the AI-Energy Nexus
| Theme | Latest Development | Why It Matters |
|---|---|---|
| Copper | Tía María permit revoked in Peru | Potentially tighter project pipeline and higher scrutiny on Andean supply risk |
| Uranium | Burke Hollow restart; Oregon project advances | Reinforces U.S. domestic supply and nuclear-linked energy security narrative |
| Lithium | Q2 Metals posts 295Mt Cisco resource | Supports Canada’s role in allied lithium supply development |
| AI-led Exploration | KoBold expands DRC search with $50M program | Shows AI tools moving upstream into mineral discovery at scale |
Why today’s mix matters
Taken together, today’s stories reinforce a wider shift in mining strategy. Copper projects are facing rising political and permitting pressure just as electrification demand remains firm. Uranium is regaining strategic importance as hyperscalers and utilities look for reliable, low-carbon power options. Lithium, meanwhile, is increasingly a story about jurisdiction, scale, and processing pathways rather than headline demand alone.
For operators, the message is that project execution risk now sits alongside grade and scale as a core valuation driver. For investors and policymakers, the signal is that the AI-energy buildout is becoming more physically constrained by mine permits, power systems, and regional politics.