The strategic landscape of North American critical minerals underwent a fundamental shift this morning. At 4:30 AM ET, Teck Resources Limited (TSX: TECK.A and TECK.B, NYSE: TECK) and the Canada Growth Fund (CGF) announced a landmark C$850 million investment framework to transform Trail Operations into a global powerhouse for specialty metals.
The agreement, which includes an equity-like investment of up to C$400 million from the CGF, is designed to double the facility’s output of germanium and antimony while introducing commercial-scale gallium production. For the mining industry, this is not just a capital expenditure announcement; it is the definitive “Trail Playbook”: a high-stakes response to Chinese export controls and a blueprint for how Western governments are now directly financing the midstream processing gap.
The Trinity of Criticality: Germanium, Antimony, and Gallium
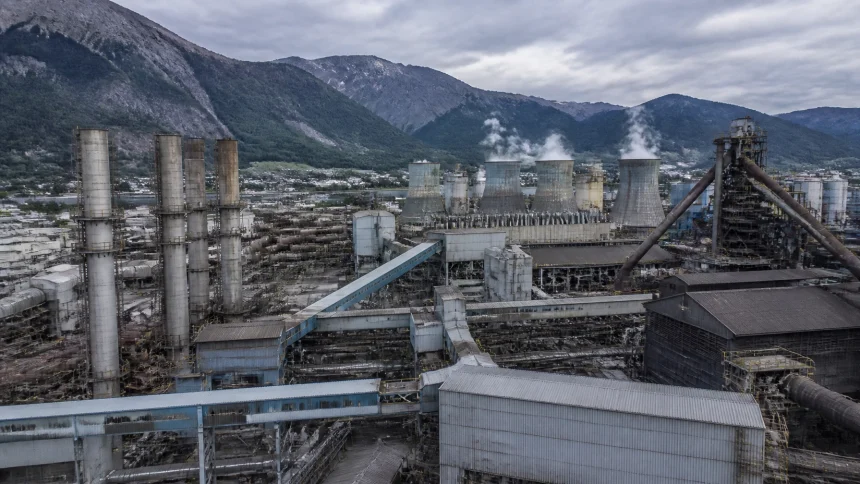
To understand why a smelter in southern British Columbia has become the focal point of North American defense and tech policy, one must look at the metals themselves. Trail Operations is already Canada’s only producer of refined germanium and antimony, as well as North America’s largest.
Germanium: The AI and Defense Backbone
Currently trading near $6,000/kg, germanium is indispensable for the high-speed fiber-optic cables that carry the world’s data and the infrared optics required for modern night-vision and satellite sensors. More critically, germanium-based semiconductors are a cornerstone of next-generation AI chip architectures. As the world pivots toward AI-driven data center demand, securing a non-Chinese source of germanium tetrachloride and germanium dioxide is no longer optional.

Antimony: The Flame and the Force
Antimony, traditionally used as a flame retardant, has seen its strategic value skyrocket due to its role in ammunition primers, infrared sensors, and high-capacity liquid metal batteries. With China and Russia controlling a combined 70% of global production, the doubling of Trail’s antimony recovery is a direct hedge against supply chain weaponization.
Gallium: The New Addition
Perhaps the most significant part of the C$850 million plan is the addition of gallium production. Gallium is the “secret sauce” of high-frequency telecommunications and military radar systems (AESA). Until now, North American gallium supply has been almost entirely reliant on imports. By integrating gallium recovery into its existing zinc circuit, Teck is closing a critical loop in the domestic semiconductor supply chain.
The Geopolitical Counter-Move
The timing of this investment is a direct response to the escalating “metal wars” of the mid-2020s. In late 2023 and throughout 2024, China initiated a series of export licensing requirements for germanium, gallium, and antimony. These moves were widely interpreted as leverage against U.S. and allied restrictions on advanced computing chips.
“The Trail Playbook is about strategic autonomy,” says a source close to the negotiations. “By doubling capacity at an existing, world-class facility, Canada and its partners are bypassing the decade-long lead times required to permit and build new ‘greenfield’ processing plants.”
Trail’s advantage lies in its feedstocks. The facility processes zinc and lead concentrates from Teck’s Red Dog mine in Alaska and has recently explored cooperation with Titan Mining’s Empire State Mines in New York to recover germanium from waste streams. This “closed-loop” North American system: mined in the U.S., refined in Canada: creates a tariff-free, CUSMA-protected supply chain that is immune to overseas export bans.
The Financial Structure: A New Model for Mining Finance
The C$850 million deal is being hailed as the inaugural success of the Canada Critical Minerals Accelerator (CCMA). The structure is notably different from traditional debt or equity raises:
- Equity-Like Investment: The Canada Growth Fund (CGF) is providing up to C$400 million in capital that behaves like equity, allowing the government to share in the upside while providing Teck with the low-cost capital needed for complex metallurgical upgrades.
- Offtake Rights: In exchange for the investment, the Government of Canada secures the right to a portion of the future output. This ensures that domestic defense and tech manufacturers have “first-call” on these metals during periods of global shortage.
- Modernization Focus: The remaining C$450 million from Teck will go toward sustaining and enhancing the broader smelter complex, which has been in operation since 1912.

This model mirrors recent government interventions in the rare earth space. For instance, Arafura Rare Earths’ recent FID was made possible by multi-billion dollar loan guarantees from the Australian government. Similarly, Lynas Rare Earths has leaned on U.S. Department of Defense funding to build processing capacity in Texas. The Teck/CGF deal proves that North America is finally willing to use its balance sheet to compete with state-backed enterprises in the East.
Comparison of Government-Led Critical Mineral Deals (2024-2026)
| Project | Metal Focus | Government Entity | Funding Type | Strategic Goal |
|---|---|---|---|---|
| Teck Trail Ops | Ge, Sb, Ga | Canada Growth Fund (CGF) | C$400M Equity-like | Counter China Export Bans |
| Arafura Nolans | NdPr (Rare Earths) | Export Finance Australia | A$840M Loan/Grant | REE Supply Chain Security |
| Lynas Seadrift | HREE (Heavy REEs) | U.S. Dept of Defense | $258M Grant | Domestic REE Refining |
| Lithium Americas | Lithium | U.S. Dept of Energy | $2.26B Loan | EV Battery Independence |
2026 Outlook: Why Trail Matters to Investors
For mining professionals and investors, the Trail expansion is a signal that “by-product” chemistry is now a frontline asset. Historically, germanium and antimony were seen as minor value-adds to Teck’s massive zinc and lead business. In 2026, these “minor” metals are the primary drivers of strategic valuation.
The ability of Trail to scale production without the environmental footprint of a new mine is a major ESG win. By extracting more value from existing concentrate streams, Teck is maximizing “resource efficiency”: a term increasingly used by institutional investors to grade mining companies on their future-readiness.

However, risks remain. The project is still subject to the negotiation of definitive agreements and regulatory approvals. Furthermore, the volatility of the specialty metals market: where prices can swing wildly based on a single policy change in Beijing: means that the offtake structure with the Canadian government is a necessary safety net for Teck’s shareholders.
Conclusion
The C$850 million Trail Playbook represents the end of the “hands-off” era for North American resource policy. By backing the doubling of germanium and antimony production, Canada is making a clear statement: midstream processing is the new high ground in the global mineral race. As Trail begins its transformation, the rest of the industry will be watching to see if this public-private “equity” model can be replicated for other critical minerals across the continent.