As the global computing landscape undergoes a structural shift toward generative artificial intelligence, the physical infrastructure supporting this digital leap has become increasingly mineral-intensive. In 2026, the "AI Energy Nexus" is no longer a theoretical concept for mining executives; it is a primary driver of demand that is reshaping commodity markets.
Data centers, which once accounted for roughly 1.5% of global power consumption, are projected to reach 1,000 TWh by 2030. In the United States alone, data center load growth is expected to consume up to 12% of total electricity by 2028. This rapid expansion of high-density computing clusters requires a massive influx of specialized raw materials. From the massive copper busbars feeding power to server racks to the rare earth magnets driving cooling systems, the AI revolution is fundamentally a mining story.
Here is the 2026 Weekly Power List: the 10 most critical minerals underwriting the AI revolution.
1. Copper: The Unrivaled Conductor
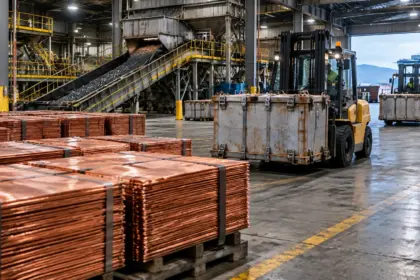
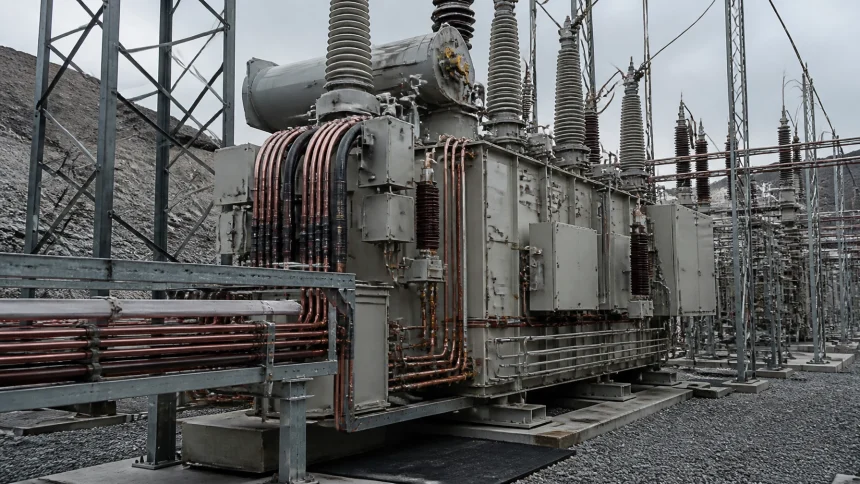
Copper remains the foundational metal of the AI build-out. Every hyperscale data center depends on copper-heavy power systems, including high-capacity grid connections, transformers, and switchgear. Beyond the power room, copper is essential for the thermal management of high-performance GPUs (Graphics Processing Units) through advanced heat sinks and vapor chambers.
By 2026, copper demand from AI data centers has moved from a marginal factor to a core market pillar. Industry analysts estimate that AI infrastructure could represent 2–3% of global refined copper demand by the end of the decade, adding hundreds of thousands of tonnes of new demand to an already tight market.
2. Uranium: Firm Power for Hyperscale Needs
The surge in 24/7 power demand from AI campuses has forced tech giants to look beyond intermittent renewables. In 2026, the resurgence of nuclear energy as a "clean firm" power source is well underway. Major cloud providers are increasingly securing long-term power purchase agreements (PPAs) with nuclear operators to ensure stable, carbon-free baseload power.
This shift has direct implications for uranium production. As companies like Energy Fuels (TSX: EFR) ramp up to meet mid-year production targets, the long-term demand floor for uranium is being supported by the persistent, high-uptime requirements of the AI sector.

3. Silver: Conductivity at the Server Edge
While silver is synonymous with the solar PV industry, its role in AI server hardware is critical due to its unmatched electrical conductivity. Silver is used in high-reliability electrical contacts, specialized solders, and coatings within the serverboards and networking gear that facilitate the high-speed data transfer required for AI training.
Additionally, the trend of co-locating data centers with dedicated solar farms ensures that silver remains a vital component of the broader AI energy ecosystem. The U.S. currently maintains a 64% import reliance on silver, highlighting a significant supply chain vulnerability for domestic infrastructure.
4. Antimony: The Critical Safety Link
Antimony has moved into the spotlight as a niche but indispensable mineral for data center safety. Its primary application is in flame retardants for the vast networks of cable sheathing and plastic enclosures within high-density server racks. As power density per rack climbs to 100kW and beyond, the risk of thermal runaway makes fire-suppression materials paramount.
Recent geopolitical shifts and export controls have led to an antimony squeeze, prompting operators to re-evaluate their reliance on single-source suppliers.
5. Heavy Rare Earth Elements (HREEs): Magnetic Precision
Heavy Rare Earth Elements, particularly dysprosium and terbium, are essential for the high-performance permanent magnets used in data center cooling systems. These magnets drive the high-efficiency motors for pumps and fans that prevent overheating in liquid-cooled AI clusters.
The USGS currently notes an 80% import reliance on rare earths for data storage and magnet applications. As AI increases the demand for high-performance cooling, the strategic importance of diversifying rare earth supply chains has become a top priority for Western policymakers and mining operators alike.

6. Lithium: Solving the Intermittency Gap
While the automotive sector remains the primary consumer of lithium, the "AI-Energy Nexus" is creating a new demand leg: Battery Energy Storage Systems (BESS). To manage the peak load requirements of AI workloads and to smooth out the intermittency of the renewable energy powering them, data centers are installing massive on-site battery arrays.
Lithium-ion chemistries are the preferred choice for these high-power, rapid-response backup systems, gradually displacing traditional lead-acid batteries in modern facility designs.
7. Tin: The Molecular Glue of AI Hardware
Tin is often overlooked, but it is the "glue" that holds AI hardware together. It is the primary component in the lead-free solder used to mount advanced processors, such as Nvidia's Blackwell series or AMD's Instinct accelerators, onto high-density circuit boards. The increased complexity and number of layers in modern AI server boards translate directly to higher tin consumption per unit.
8. Aluminum: Managing High-Density Heat
Aluminum’s role in the AI revolution is twofold: lightweight infrastructure and thermal management. Large-scale heat sinks, used to dissipate the immense heat generated by AI chips, are primarily composed of aluminum due to its favorable thermal conductivity-to-weight ratio. Furthermore, the massive structural frames of hyperscale facilities and the high-voltage transmission lines connecting them to the grid utilize vast quantities of aluminum.

9. Gallium: The Efficiency Frontier
Next-generation power electronics are increasingly moving away from silicon in favor of Gallium Nitride (GaN). In the context of AI data centers, GaN-based power supply units (PSUs) offer significantly higher efficiency and smaller footprints than traditional silicon components. By reducing power conversion losses, gallium-enriched components allow for more compute power to be packed into existing facility envelopes.
10. Graphite: Anode Stability for Grid Storage
As a key component of the anodes in lithium-ion batteries, graphite is essential for the utility-scale storage projects that support data center operations. Whether it is synthetic graphite for high-performance cycling or natural graphite for bulk storage, the stability of the graphite supply chain is critical for the "green" AI transition.
Market Snapshot: AI Energy Nexus Data Points (2026 Outlook)
| Mineral | Key AI/Data Center Application | 2026 Strategic Outlook |
|---|---|---|
| Copper | Power distribution, heat sinks | Structural deficit; high demand growth |
| Uranium | 24/7 low-carbon baseload power | Bullish; nuclear PPA growth among tech firms |
| Silver | Server boards, solar PV supply | High import reliance; supply chain risk |
| Antimony | Fire retardants, semiconductors | Supply squeeze; geopolitical price volatility |
| HREEs | High-temp cooling motor magnets | Critical; focus on non-Chinese supply |
| Lithium | BESS (Grid-balancing backup) | Steady growth; diversification of chemistries |
Conclusion: The Supply Chain Imperative
The convergence of high-performance computing and heavy industry has created a new paradigm for the mining sector. For investors and operators, staying ahead of these trends is no longer optional. As AI continues to evolve, the demand for these ten minerals will likely intensify, placing a premium on secure, domestic, and ESG-compliant mining operations.
The AI revolution is not just happening in the cloud; it is being forged in the pits and processing plants of the global mining industry.

Social Media Snippet (LinkedIn/X):
Is your portfolio ready for the AI-Energy Nexus? From Copper deficits to the Antimony squeeze, 10 minerals are underwriting the compute revolution in 2026. Discover why mining is the real backbone of AI. #MiningNews #CriticalMinerals #AIConsumption #CopperDemand #Uranium #EnergyTransition