When spot gold slipped below US$4,000 per troy ounce on Friday, October 23, 2026—closing at US$3,993.96 per ounce after the London bullion fixing recorded US$4,026.70 per ounce—the pullback prompted an immediate question across mining boardrooms and institutional credit desks: did the mining industry spend the first half of 2026 overpaying for acquisitions at the top of the cycle (Trading Economics; Engineering News; Westmetall Market Data)? Yet framing 2026 capital allocation around January’s price peak obscures the actual financial mechanics governing the industry’s largest commitments. On Thursday, October 22—twenty-four hours before spot gold breached US$4,000—Newmont Corporation unveiled updated feasibility metrics for its proposed Red Chris Block Cave expansion in British Columbia, outlining an estimated US$4.2 billion to US$4.8 billion development capital outlay (100 percent project basis) evaluated across economic scenarios that include US$3,600 per ounce gold and US$5.00 per pound copper (TradingKey / Newmont Q3 Call; Imperial Metals). The decisive test facing mining finance as 2026 enters its final two months is not who transacted when gold traded above US$5,300, but whose capital-allocation models were engineered to withstand a full commodity cycle.
Establishing an accurate baseline for the 2026 gold pullback requires strict benchmark discipline. Earlier market commentary mixed incompatible price series, comparing an intraday COMEX continuous futures high of US$5,318.40 per ounce on January 29, 2026 against an October 23 LBMA spot close of US$3,993.96 per ounce (or an October 14 COMEX close of US$4,122.40 per ounce). While arithmetic on those selected numbers yields a 24.9 percent difference, comparing a futures intraday high against a spot close across different windows violates like-for-like market measurement. Measured strictly on a single, consistent benchmark—the daily LBMA Gold London Fixing compiled by Westmetall—gold reached its 2026 peak fixing of US$5,501.70 per ounce on January 29, 2026 and closed January at US$5,063.45 per ounce. Subsequent month-end London fixings tracked a non-linear correction: US$5,174.10 on February 27, US$4,553.95 on March 31, US$4,625.80 on April 30, US$4,525.75 on May 29, and a mid-year low of US$4,016.70 on June 30. After rebounding to US$4,052.20 on July 31 and US$4,602.00 on August 28, the London fixing retreated to US$4,188.75 on September 30 and settled at US$4,026.70 per ounce on October 23, 2026 (Westmetall London Fixing; Westmetall Market Data). On that validated like-for-like London Fixing basis, gold declined by US$1,475.00 per ounce, or 26.8 percent, from its January 29 peak to October 23, before trading near US$4,006.55 spot and US$4,025 COMEX futures on Monday, October 26 (Trading Economics; Business Standard).
For operating producers, however, a 26.8 percent retreat from a single-day January spike has not created financial distress, because neither quarterly cash flows nor corporate reserve models were built on US$5,500 gold. In its third-quarter 2026 results released on October 22, Newmont reported an average realized gold price of US$4,317 per ounce in Q3 2026 (including a gross sales price of US$4,291 per ounce and a positive mark-to-market provisional pricing adjustment of US$26 per ounce), down slightly from US$4,414 in Q2 and US$4,900 in Q1, for a nine-month year-to-date average of US$4,546 per ounce compared with US$3,498 per ounce for full-year 2025. With Q3 gold by-product Costs Applicable to Sales (CAS) at US$832 per ounce (co-product CAS of US$1,449 per ounce) and by-product All-In Sustaining Costs (AISC) at US$1,454 per ounce (co-product AISC of US$1,963 per ounce)—and full-year 2026 by-product AISC guidance improved by 10 percent to US$1,520 per ounce under a US$4,500 per ounce gold assumption—Newmont generated US$2.8 billion in net cash from operating activities and US$1.9 billion in Q3 free cash flow, bringing nine-month 2026 free cash flow to US$7.261 billion (Newmont Q3 Release). Even more conservatively, Newmont’s 2025 mineral reserves of 118.2 million attributable ounces are booked at US$2,000 per ounce gold, with measured and indicated resources of 88.1 million ounces booked at US$2,300 per ounce, and management typically anchors annual reserve pricing to a three-year trailing average rather than spot peaks (TradingKey / Newmont Q3 Call).
Against this backdrop, a forensic examination of two headline 2026 mining M&A transactions—Eldorado Gold’s acquisition of Foran Mining and Zijin Mining Group’s terminated buyout of Allied Gold—demonstrates why a simplistic “peak-buying hangover” thesis fails under scrutiny. Both deals were announced within days of gold’s January 2026 highs, yet neither transaction’s financial trajectory was governed by a US$5,300 or US$5,500 gold price deck.
Consider first Eldorado Gold Corporation’s acquisition of Foran Mining Corporation, announced on February 2, 2026 and completed via a court-approved plan of arrangement on April 14, 2026 (McCarthy Tétrault). Under the Arrangement Agreement, Foran shareholders received 0.1128 Eldorado common shares plus C$0.01 in cash per Foran share, implying an equity value of approximately C$3.8 billion (about US$2.8 billion) (Geomechanics.io). Three features help explain Eldorado–Foran’s acquisition rationale, although its financing risks extend beyond shareholder dilution. First, pricing discipline at announcement was tight: the consideration represented an 8.0 percent premium to the 20-day volume-weighted average trading prices (VWAP) ended January 30, 2026, and a nil (0 percent) premium to Foran’s closing TSX share price on January 30 (Eldorado Gold). Second, because the deal was structured as an all-share transaction (leaving legacy Eldorado and Foran shareholders holding 76 percent and 24 percent of the combined company, respectively), Eldorado paid Foran shareholders principally in shares rather than through a large new cash acquisition payment. However, its June 30, 2026 interim statements report approximately US$355 million in financing obligations assumed in the Foran acquisition, including a fully drawn US$250 million Sprott facility secured by the acquired assets and subject to covenants. Eldorado reported compliance at June 30. The deal therefore brought inherited debt and covenant exposure as well as equity dilution (Eldorado Gold, Q2 2026 interim financial statements).
Third, and most fundamentally, Foran’s cornerstone asset—the McIlvenna Bay project located 65 kilometers west of Flin Flon in eastern Saskatchewan—is not a primary gold mine (Eldorado Gold). It is a copper-zinc-gold-silver volcanogenic massive sulfide (VMS) deposit in the Flin Flon Greenstone Belt whose feasibility economics are driven primarily by copper and zinc, with gold and silver serving as precious-metal credits. By pairing Eldorado’s Skouries copper-gold development in Greece with Foran’s McIlvenna Bay in Saskatchewan—both having produced first concentrates, with commercial production expected in Q4 2026—the combined company projected 2027 output of roughly 900,000 gold-equivalent ounces (~77 percent gold, ~15 percent copper, ~8 percent other metals), generating an estimated US$2.1 billion in 2027 EBITDA and US$1.5 billion in 2027 free cash flow (Eldorado Gold). Footnote 1 of the February 2 announcement discloses the exact street consensus prices underlying those 2027 projections: US$3,965 per ounce gold, US$5.02 per pound copper, US$47.54 per ounce silver, and US$1.26 per pound zinc (Eldorado Gold). Even after gold’s retreat to US$3,993.96 spot (US$4,026.70 London fixing) on October 23 and with LME copper above US$14,200 per tonne (US$6.45+ per pound), market prices for both gold and copper remain above the consensus assumptions embedded in the Eldorado–Foran model. A comparable consolidation rationale underpinned Coeur Mining’s all-stock acquisition of New Gold Inc., which was originally announced on November 3, 2025—months before the January 2026 gold peak—and closed on March 20, 2026 to combine the New Afton copper-gold mine in British Columbia and the Rainy River gold mine in Ontario into a senior North American producer.
The second major transaction of 2026—Zijin Gold International’s proposed C$5.5 billion (US$4.01 billion) all-cash acquisition of Allied Gold Corporation—illustrates a completely different transaction risk: sovereign regulatory completion. Signed in January 2026 at C$44.00 per share (a 27 percent premium), the deal would have transferred control of Allied Gold’s producing mines in Mali and Côte d’Ivoire alongside the flagship Kurmuk Gold Mine development in Ethiopia’s Benishangul-Gumuz Region (projected to produce 240,000–270,000 ounces per year starting in 2027). On July 29–30, 2026, however, the parties mutually terminated the C$5.5 billion takeover (Demócrata).
Attributing the Zijin–Allied termination to falling gold prices is contradicted by documentary evidence. On July 30, 2026, the LBMA Gold London Fixing stood at US$4,061.50 per ounce and rallied to US$4,634.20 per ounce by August 24 (Westmetall London Fixing). More importantly, the joint termination announcement explicitly cited the failure to obtain Chinese regulatory approvals prior to the July 29, 2026 outside date, concluding there was no reasonable likelihood that closing conditions would be met within a reasonable timeframe amid tighter Beijing oversight of outbound foreign acquisitions (Demócrata). Rather than abandoning Allied Gold’s assets, Zijin immediately replaced the full buyout with a smaller transaction that did not require the same sovereign clearance: a US$295 million (C$417 million) private placement acquiring 12.8 million newly issued Allied shares at C$32.55 per share for a 9.2 percent strategic stake (Banks Ethiopia). The lesson of Zijin–Allied is not that buyers overpaid at the gold peak, but that cross-border cash takeovers by state-linked acquirers face acute regulatory execution risk, forcing developers to pivot to minority equity placements to fund capital-intensive builds like Kurmuk.
If neither Eldorado–Foran nor Zijin–Allied proves reckless peak-cycle M&A, how are major producers evaluating multi-billion-dollar capital commitments in late 2026? The answer lies in Newmont’s October 22, 2026 update on the Red Chris Block Cave project in British Columbia’s Golden Triangle, operated by Newmont (70 percent interest) in joint venture with Imperial Metals Corporation (30 percent interest).
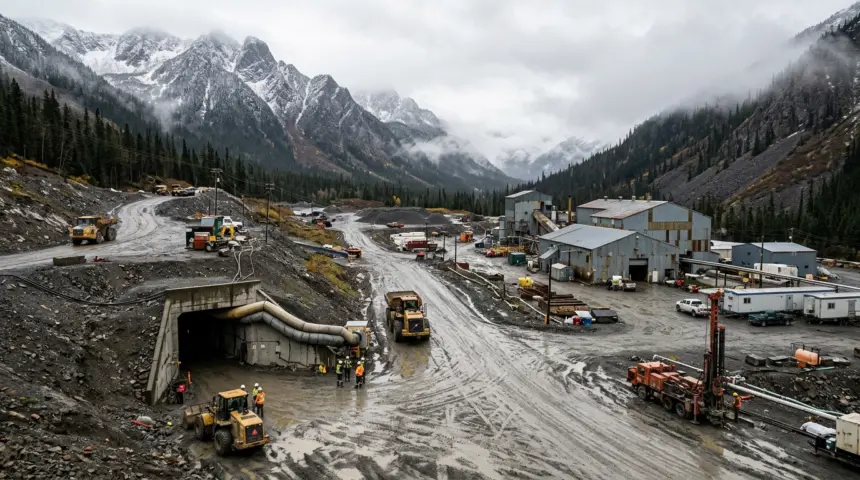
Red Chris is not a greenfield build; it is an existing open-pit copper-gold mine with established road access, camp facilities, tailings storage, export access via the Port of Stewart, and clean hydroelectric power from BC Hydro (Imperial Metals). However, the existing open pit is experiencing natural grade depletion: in Q3 2026, Red Chris produced 14.771 million pounds of copper and 12,391 ounces of gold (100 percent basis), down 29 percent and 43 percent year-over-year, respectively, from 20.900 million pounds of copper and 21,660 ounces of gold in Q3 2025, as lower grades and recoveries offset a 17 percent throughput increase (Imperial Metals). Analysts must never confuse the elevated unit costs of the current open-pit transition phase with the forecast economics of the deep underground block cave.
To mine the higher-grade porphyry system beneath the open pit, Newmont is finalizing a definitive feasibility study for a brownfield underground block-cave expansion, targeting a full-funds Final Investment Decision (FID) in early 2027 (TradingKey / Newmont Q3 Call). On a 100 percent project basis, Newmont estimates development capital at US$4.2 billion to US$4.8 billion. Careful reading of Footnote 3 in the October 22 disclosure is essential: the US$4.2–US$4.8 billion estimate (converted at C$1.00 = US$0.75) includes contingency and is presented net of C$500 million in anticipated Canadian federal critical-minerals grant support announced in July 2026 (expected to be finalized before year-end 2026), meaning gross upfront capital approaches US$4.6–US$5.2 billion (~C$6.1–C$6.8 billion), and the estimate excludes costs to transition from open-pit to block-cave operations (Imperial Metals; Mining.com.au). Newmont’s 70 percent attributable share equates to roughly US$2.94–US$3.36 billion net of the federal grant, while 30 percent partner Imperial Metals faces an attributable capital requirement of US$1.26–US$1.44 billion pending its forthcoming NI 43-101 technical report.
Why is Newmont preparing to commit up to US$4.8 billion (100 percent basis) for a project where construction begins in 2027, first cave production is targeted for 2033, and peak output arrives in 2035–2040? The strategic case rests on three pillars: multi-decade district scale, copper co-product economics, and internal cash-flow self-funding. First, the initial 13-year cave phase will produce 3.0 million ounces of gold and over 1.8 billion pounds of copper (100 percent basis), ramping up between 2035 and 2040 to average 275,000–325,000 ounces of gold and 145–187 million pounds of copper annually while expanding mill capacity to 15 million tonnes per year (Imperial Metals). Critically, 40 percent of the upfront investment in processing and material-handling infrastructure supports subsequent macro-block caves and East Ridge, laying the foundation for a potential 70-year mine life, backed by an amended B.C. Environmental Assessment Certificate secured in June 2026 through a consent agreement with the Tahltan Nation (Imperial Metals).
Second, Newmont expects Red Chris to deliver a double-digit internal rate of return (IRR) above its country-specific discount rate, noting in Footnote 4 that the project was evaluated across a range of economic scenarios, including US$3,600 per ounce gold and US$5.00 per pound copper (TradingKey / Newmont Q3 Call; Imperial Metals). While US$3,600 gold and US$5.00 copper represent one evaluation scenario rather than an established corporate price floor or a guaranteed return at those exact prices, spot gold on October 23 (US$3,993.96; fixing US$4,026.70) still sits roughly US$400 per ounce above US$3,600, and LME copper (US$6.47/lb) sits nearly 30 percent above US$5.00/lb.
Third, Newmont can self-fund the ramp-up within its capital allocation framework, which prioritizes US$1.95 billion in 2026 sustaining capital, a US$1.1 billion annual base dividend (US$0.26 per share in Q3), US$1.4 billion in 2026 development capital, and ratable share repurchases (US$1.6 billion executed since July 23, with US$2.8 billion remaining under its US$6.0 billion program, having reduced total share count by over 115 million shares or 10 percent since February 2024) (Newmont Q3 Release). Ending Q3 2026 with US$8.8 billion in cash, US$12.8 billion in liquidity, and US$3.2 billion in net cash (before the planned US$1.95 billion Q4 payment to Barrick under the amended Nevada Gold Mines agreement bringing in Fourmile, Fiberline, and Mike), Newmont expects 2027 development capital to rise by US$500 million over 2026—half for Red Chris—with US$200 million offset in 2027 (and US$400 million annually from 2028) as Yanacocha water-treatment spending winds down and Cadia PC2-3 and Tanami Expansion 2 complete construction (TradingKey / Newmont Q3 Call).
What development would materially change this article’s conclusion? A sustained collapse in gold and copper below Newmont’s evaluation scenarios prior to early 2027, failure to finalize the C$500 million federal grant, or financing distress for 30 percent partner Imperial Metals could alter Red Chris’s sanctioning structure, whereas Q1 2027 Joint Venture FID approval and on-budget commissioning at McIlvenna Bay and Skouries would validate disciplined cycle-tested capital allocation.
Three Key Takeaways (Gold / Mining Finance)
- Validated Benchmark Correction (-26.8% on London Fixing): Measured strictly on a single consistent benchmark (LBMA Gold London Fixing via Westmetall), gold declined by US$1,475.00/oz (-26.8 percent) from its January 29, 2026 peak fixing of US$5,501.70/oz to US$4,026.70/oz on October 23, 2026 (with October 23 spot closing at US$3,993.96/oz), leaving Q3 producer realized prices (US$4,317/oz at Newmont) and reserve decks (US$2,000/oz) highly profitable.
- 2026 M&A Deals Disprove the “Peak-Buying Hangover” Thesis: Eldorado Gold’s C$3.8 billion all-share acquisition of Foran Mining (0.1128 shares + C$0.01 cash; 8.0 percent 20-day VWAP premium; existing Foran debt and covenants assumed) was underwritten by McIlvenna Bay’s copper-zinc VMS economics at consensus assumptions of US$3,965/oz Au and US$5.02/lb Cu, while Zijin’s C$5.5 billion cash offer for Allied Gold was terminated on July 29–30 due to Chinese regulatory approval delays and replaced by a US$295 million (9.2 percent) equity placement at C$32.55/share.
- Newmont’s Red Chris $3,600/oz Scenario Is a Multi-Scenario Stress Test, Not a Guaranteed Floor: Newmont’s proposed US$4.2–US$4.8 billion Red Chris Block Cave expansion (100 percent basis, net of C$500 million federal grant support, excluding open-pit transition costs; Newmont 70 percent, Imperial Metals 30 percent) targets 3.0 Moz Au and >1.8B lbs Cu over an initial 13-year cave life starting in 2033, evaluated across scenarios including US$3,600/oz Au and US$5.00/lb Cu.
Chart 04 & Major 2026 Transactions Comparison Table
| Transaction / Capital Commitment | Acquirer / Operator & Target / Partner | Headline Value & Financing Structure | Disclosed Metal Price Assumptions | Primary Asset & Geological Profile | Current Status & Verified Risk Exposure (Oct 2026) |
|---|---|---|---|---|---|
| Foran Mining Acquisition (Announced Feb 2, 2026; Closed Apr 14, 2026) | Eldorado Gold (76%) / Foran Mining (24%) | ~C$3.8B (US$2.8B) equity value; 0.1128 ELD shares + C$0.01 cash (8% 20-day VWAP premium; 0% spot close premium); All-share consideration; assumed Foran debt incl. US$250M Sprott facility | 2027 Consensus: US$3,965/oz Au, US$5.02/lb Cu, US$47.54/oz Ag, US$1.26/lb Zn | McIlvenna Bay (Saskatchewan) Cu-Zn-Au-Ag VMS deposit + Skouries (Greece) Cu-Au | Closed; targeting Q4 2026 commercial production and ~900 koz GEO (US$1.5B FCF) in 2027; equity dilution plus assumed debt/covenant exposure |
| Allied Gold Takeover & Revised Placement (Jan 2026; Terminated Jul 30, 2026) | Zijin Gold International / Allied Gold Corp. | C$5.5B (US$4.01B) all-cash bid at C$44.00/sh (27% premium) terminated; replaced by US$295M (C$417M) equity placement (12.8M shares at C$32.55 for 9.2% stake) | Not driven by gold deck re-pricing (London Fixing was US$4,061.50/oz on Jul 30 and rose in Aug) | Kurmuk (Ethiopia, 240k–270k oz/yr Au from 2027) + Mali & Côte d’Ivoire mines | Terminated due to unfulfilled Chinese regulatory approvals by Jul 29 outside date; minority equity closed Aug 2026 |
| New Gold Acquisition (Announced Nov 3, 2025; Closed Mar 20, 2026) | Coeur Mining / New Gold Inc. | All-stock North American senior consolidation announced prior to Jan 2026 gold peak | Multi-year reserve/consensus deck set in Nov 2025 | New Afton (B.C. Cu-Au block cave) & Rainy River (Ontario Au) | Completed Mar 20, 2026; integrated into 2026 consolidated guidance |
| Red Chris Block Cave Expansion (Update Oct 22, 2026; FID Expected Early 2027) | Newmont Corp. (70% operator) / Imperial Metals (30% JV partner) | US$4.2B–$4.8B (100% basis, net of C$500M federal grant, incl. contingency, excl. open-pit transition costs); self-funded by Newmont ($8.8B cash) | Evaluated across scenarios including US$3,600/oz Au and US$5.00/lb Cu (2026 guidance base: $4,500 Au, $5.00 Cu) | Red Chris (B.C. Golden Triangle) brownfield deep porphyry block cave (15 Mtpa mill) | Feasibility nearing completion; 2027 construction start, 2033 first cave output; 40% infra supports up to 70-yr life |
| Observation Date (2026) | LBMA Gold London Fixing (US$/oz via Westmetall) | Cumulative Change vs. Jan 29 Peak Fixing | Reference Corporate / Project Benchmark Comparison |
|---|---|---|---|
| Jan 29, 2026 (Peak) | $5,501.70 | — | 2026 London Fixing high (COMEX continuous high: $5,318.40) |
| Jan 30, 2026 | $5,063.45 | -$438.25 (-8.0%) | Eldorado–Foran 20-day VWAP period ended Jan 30 |
| Feb 27, 2026 | $5,174.10 | -$327.60 (-6.0%) | Eldorado–Foran announced Feb 2 |
| Mar 31, 2026 | $4,553.95 | -$947.75 (-17.2%) | Coeur–New Gold closed Mar 20; Newmont Q1 avg realized $4,900/oz |
| Apr 30, 2026 | $4,625.80 | -$875.90 (-15.9%) | Eldorado–Foran closed Apr 14 |
| May 29, 2026 | $4,525.75 | -$975.95 (-17.7%) | Above Newmont $4,500/oz 2026 guidance assumption |
| Jun 30, 2026 | $4,016.70 | -$1,485.00 (-27.0%) | Mid-year fixing trough; Newmont Q2 avg realized $4,414/oz |
| Jul 31, 2026 | $4,052.20 | -$1,449.50 (-26.3%) | Zijin–Allied terminated Jul 29–30 (Jul 30 fixing: $4,061.50) |
| Aug 28, 2026 | $4,602.00 | -$899.70 (-16.4%) | Late-summer rebound (Aug 24 fixing: $4,634.20) |
| Sep 30, 2026 | $4,188.75 | -$1,312.95 (-23.9%) | Newmont Q3 avg realized $4,317/oz ($4,546/oz YTD) |
| Oct 23, 2026 | $4,026.70 | -$1,475.00 (-26.8%) | Spot close $3,993.96/oz; sits +$426.70/oz above $3,600 Red Chris scenario |
Primary Sources
- Newmont Corporation Q3 2026 Results & Red Chris Block Cave Update — SEC Form 8-K (Oct 22–23, 2026): https://www.sec.gov/Archives/edgar/data/1164727/000116472726000041/newmontq32026earningsrelea.htm
- Newmont Corporation Q3 2026 Full Press Release — Junior Mining Network: https://www.juniorminingnetwork.com/junior-miner-news/press-releases/1101-nyse/nem/213412-newmont-reports-third-quarter-2026-results-with-record-third-quarter-adjusted-net-income-positioned-to-achieve-full-year-guidance-provides-update-on-red-chris-block-cave-project.html
- Newmont Q3 2026 Earnings Call Transcript Summary — TradingKey: https://www.tradingkey.com/news/transcripts/262234410-tradingkey
- Imperial Metals — Red Chris Block Cave Planning Progress & Q3 2026 Production (Oct 22, 2026): https://imperialmetals.com/imperial-reports-red-chris-mine-block-cave-planning-progress-and-2026-third-quarter-production-update/
- Eldorado Gold & Foran Mining C$3.8B Arrangement Agreement Release (Feb 2, 2026): https://www.eldoradogold.com/investors/news-releases/eldorado-and-foran-combine-create-leading-gold-and-copper-producer
- McCarthy Tétrault — Foran Acquired by Eldorado for C$3.8B (Closed Apr 14, 2026): https://www.mccarthy.ca/en/experience/foran-acquired-by-eldorado-for-c-3-8b
- Eldorado Gold — June 30, 2026 Interim Financial Statements (Note 8: assumed Sprott facility, debt and covenant disclosures): https://www.sec.gov/Archives/edgar/data/918608/000091860826000023/unauditedcondensedconsolid.htm
- Zijin Abandons C$5.5B Allied Gold Takeover, Takes $295M Stake — Banks Ethiopia: https://banksethiopia.com/news/chinas-zijin-allied-gold-kurmuk-mine/
- Coeur Completes Acquisition of New Gold (Mar 20, 2026): https://www.coeur.com/investors/news/news-details/2026/Coeur-Completes-Acquisition-of-New-Gold/default.aspx
- Westmetall — Gold London Fixing Daily Historical Series (2026): https://www.westmetall.com/en/markdaten.php?action=table&field=USD_ozt_London